I have a small piece of a nice shopping center in in Rhode Island, which we bought in 2001 — before prices got out of hand. Now the syndicator writes me,
Conditions at our shopping center are bad and appear to be deteriorating. Circuit City filed for bankruptcy and vacated the property in March of last year. Pier I Imports, Sports Authority and other tenants are receiving rent reductions and as of December we have lost our warehouse tenant. Staples has indicated that they will need to shrink by about 8,000 feet (from 26,000) if we would like them to renew their lease which expires in 2010 and that it wants to pay a reduced rent as well. …
The real estate industry, especially the retail sector, is facing unprecedented economic times. The economy has suffered a deep recession; consumer spending is very weak; retail sales are at multi-year lows, and unemployment rates are very high. These factors have had a negative impact on many real estate investments, and ours have been particularly hard hit.
I’m guessing the bank may get the property. Which means it will have to sell the property to investors at some point. And those investors should get a good deal. The process of washing crappy real estate through the system will take — I’m guessing another five years. I’ve seen unbelievable bargains being sold by banks and other financial institutions. They’re typically lousy, impatient managers. The key is to cultivate your contacts. When these come down, they don’t come down in a nice, public auction like the stockmarket. They get sneaked out of the backdoor for cash and promptly forgotten. (Who wants to remember the ugly loan they made?)
Losing the shopping center depresses me. But I’ll make it up, as the economy rebounds, which it’s now clearly doing. Parts of the stockmarket — especially technology stocks — will do well this year. To make us all happy, I reprint this remarkable article from yesterday’s “gloom-and-doom” New York Times. Enjoy.
Why So Glum? Numbers Point to a Recovery
By FLOYD NORRIS of the New York Times
The American economy appears to be in a cyclical recovery that is gaining strength. Firms have begun to hire and consumer spending seems to be accelerating.
That is what usually happens after particularly sharp recessions, so it is surprising that many commentators, whether economists or politicians, seem to doubt that such a thing could possibly be happening.
Usually you can depend on the White House to view the economy with the most rose-tinted glasses available. But it was not until last week, after a strong employment report, that President Obama started to sound a little optimistic.
“The tough measures that we took — measures that were necessary even though sometimes they were unpopular — have broken this slide and are helping us to climb out of this recession,” he said in a speech at a factory making battery components in North Carolina.
Note, however, that he seemed to believe the country remained in recession. It is virtually certain that is not accurate, as least as will be determined by the arbiters of recession at the National Bureau of Economic Research. “The recession is over,” one of those arbiters, Jeffrey Frankel of Harvard, wrote this week.
But the White House is unwilling to make that claim.
Why is good news being received with such doubt? Why is “new normal” the currently popular economic phrase, signifying that growth will be subpar for an extended period, and that the old normal is no longer something to be expected?
It is possible, of course, that I am wrong and the prevalent pessimism is correct. Many economic indicators, including Thursday’s retail sales report, are looking up, but that does not prove the recovery will be self-sustaining. There are issues relating to over-indebted consumers and local governments. The housing collapse will have an impact for some time.
But there are, I think, a number of reasons for the glum outlook that are unrelated to the actual economic data.
First, the last two recoveries, after the downturns of 1990-91 and 2001, were in fact very slow to pick up any momentum. It is easy to forget that those recessions were also remarkably shallow. If you are under 45, you probably don’t have much recollection of the last strong recovery, after the recession that ended in late 1982.
Add to that the fact that the vast majority of the seers did not see this recession coming. Remember Ben Bernanke assuring us the subprime problem was “contained”? In mid-2008, after the recession had been under way for six months, the Fed thought there would be no recession, and the most pessimistic member of its Open Market Committee thought the unemployment rate could climb to 6.1 percent by late 2009. It actually went over 10 percent.
In January of this year — after the recession had probably been over for at least a few months — the most optimistic member of the committee expected the unemployment rate to fall to 8.6 percent by late this year. The consensus was for a rate no lower than 9.5 percent.
Having been embarrassed by missing impending disaster, there is an understandable hesitation to appear foolishly optimistic again.
But even without that factor, it is normal for recessions to make people pessimistic. “Go back and read what people were saying in 1982 or 1975,” said Robert Barbera, the chief economist of ITG. “Nobody was saying, ‘Deep recession, big recovery.’ It is quite normal to expect an abnormally weak recovery. It is also normal for that expectation to be wrong.”
But if that is normal, one factor that brings optimism to some forecasts is absent this time. Both Republicans and Democrats have good reasons to be negative. Republicans are loath to give President Obama credit for anything, and no doubt grate when he points to his administration’s stimulus program as a cause of the good economic news, as he did in North Carolina.
Democrats would love to give the president credit. But much of the Democratic Party wants another stimulus bill to be passed, notwithstanding worries about budget deficits. Chances for that are not enhanced by the perception the economy is getting better.
The employment report for March, released a week ago, was a milestone that has been little noted. The household survey, from which the unemployment rate is calculated, showed a gain during the first quarter of this year of 1.1 million jobs, the best performance since the spring of 2005.
True, the more widely reported numbers from the survey of employers are not as good. But those numbers are subject to heavy revision as better data becomes available. At the turning points for employment after the last two downturns, those numbers turned out to be far better than was reported at the time.
Employment is a lagging indicator. Employers can be slow to cut back when business turns down, and slow to rehire when it picks up. It stands to reason that when employers cut back sharply — as happened in this cycle — they will have to rehire faster than if they had been slow to fire, as was true in the two previous downturns.
I looked back at the recoveries after seven recessions from 1950 through 1982 and found that, on average, such a strong three-month performance of the household survey, defined as a gain of at least 0.8 percent in the total number of existing jobs, came seven months after the recession had ended, with a range of two to 13 months.
If the 2007-9 recession ended in August, as the index of coincident indicators would seem to indicate, the lag this time will have been seven months.
The lag was 28 months after the 1990-91 recession ended, and an amazing 42 months after the 2001 downturn concluded. Those really did deserve the title of “jobless recovery.” But they were very different from what appears to be unfolding now.
The stock market’s recent performance may be sending a similar message. Prices have been rising, but there is not much volume. Why? A lot of money managers are fully invested, but many investors remain fearful and are not putting cash into mutual funds. To judge from anecdotal evidence, some of the buying now is short-covering by hedge funds that expected the economy to be much weaker than it is, and thought corporate earnings reports would devastate investors. Instead, they are hearing from companies that business is stronger than expected.
Some Americans are in deep trouble, to be sure, and the days of paying for second homes by refinancing the mortgage on the first will not return soon. But many Americans — both individuals and businesses — who cut back sharply when fear was at a peak a year ago are now finding that they overreacted. The businesses need to hire to meet demand, some of it coming from individuals who are less fearful now of losing their own jobs.
In 1982, Democrats scoffed at a surging stock market and thought a severe recession would last for a very long time. They were confident that the economy would doom Ronald Reagan’s re-election campaign in 1984. All they had to do was make clear they offered a stark alternative to the failing policies of the incumbent
Change a few words (Reagan to Obama, Democrats to Republicans, 1984 to 2012) and you have an accurate description of the current political climate. Could the Republicans be as wrong now as the Democrats were then?
Nike releases a a new Tiger Woods commercial. Nike can’t drop Tiger, because too much of its business is at stake. But it can try something clever — a new commercial.
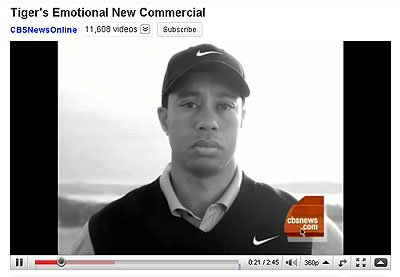
For Tiger’s commercial, click here.
Why there are no “gentile jokes?
A gentile goes into a clothing store and says, “This is a very fine jacket. How much is it?”
The salesman says, “It’s $500.”
The gentile says, “OK, I’ll take it.”
***
Two gentiles meet on the street.
The first one says, “You own your own business, don’t you? How’s it going?”
The other gentile says, “Just great! Thanks for asking!”
***
Two gentile mothers meet on the street and start talking about children.
Gentile mother 1 (said with pride): “My son is a construction worker!”
A Gentile mother 2 (said with more pride): “My son is a truck driver!”
***
A man calls his mother and says, “Mother, I know you’re expecting me for dinner this evening, but something important has come up and I can’t make it.”
His mother says, “OK.”
Harry Newton, who’s feeling happy the Australian dollar is 93 cents and climbing.

Harry, the shopping center story reminds me of our conversation a year ago when I reported the weak positions landlords have in such matters. The courts a slow to respond and Tenants walk almost with impunity. In our warehouse portfolio it's not so much a 'users market' as it is users will be the next buyers out there. They will either snatch from investors in a purchase or accomplish the same by paying rents that effectively steal properties from owners (like a purchase) anyway.