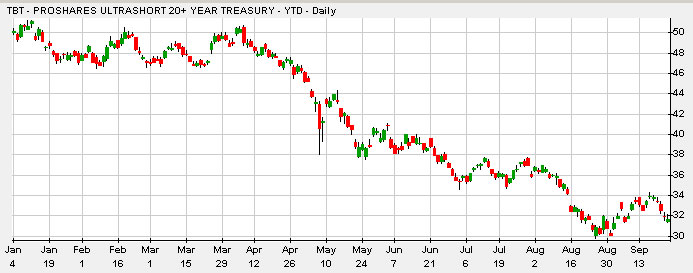
The message in the headline stands. I’m inching more into equities, including GOOG and CAT. I’m swapping into stronger muni bonds. I don’t believe interest rates will rise for a long, long time. In fact, they’re likely to keep falling. Muni bnds continue to make sense and will, as local and Federal taxes rise. Todd says take your risk in your business, not in your bond portfolio. Do not buy TBT which is a lousy bet on interest rates falling.
David Tepper was on CNBC this morning. He’s the president and founder of gigantic hedge fund Appaloosa. He’s averaged 40% or so for years. He’s positive on equities, but owns a lot of bonds and preferreds. He likes to be in the forefront. His wonderful expression: You get to feast on the grass or the lion gets to feast on me. He points out that the S&P is just under 12 times next year’s earnings. That’s low historically.
Entrepreneurial opportunities everywhere. I dined at Shake Shack last night. They have a few fast food restaurants in New York. They make the world’s best hamburgers which they make to your order:
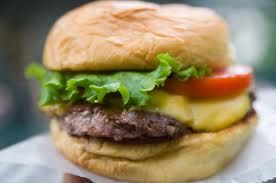
When you place your order, they give you one of these:
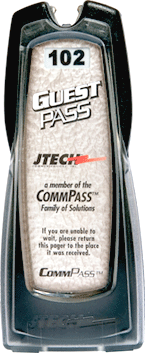
It rings and flashes when your order is ready. It’s made by a company called JTECH, which, according to its web site, “introduced the first silent server paging system for restaurants.”
Entrepreneurship is alive and well — even in hamburgers. You should have seen the line last night at 9:30 for hamburgers. It included a bunch of secret service guys in town to protect Obama who was visiting. If they eat there, it must be good. It was.
Short-term debt and retail failures (like Circuit City bankruptcy) hurt shopping center investments. But they’re coming back — sort of. The common deal is:
1. The bank reduces the size of the loan. 15% s not uncommon.
2. The bank extends the loan for another three years.
3. The equity investors pony up more money. The money gets used to flossy up the shopping center and for improvements to accommodate a new tenant.
Bingo, the place becomes financially viable again. The three-step is happening in office real estate also. All this is a positive and benefits the economy. The only problem is that banks have been slow to awaken to the new reality. Finally, they’re getting it.
Wading further into the healthcare muck. Continuing on from yesterday’s contentious column.
First, I’m not stupid, nor cheap when it comes to my health. Second, I’ll avoid dealing with Canada and Mexico. Too many horror stories. Too many unknowns. I’ll pony up the $1,000 at my local pharmacy. Third, I’ll sign up for my Medicare RX plan in November when our government decides I’m kosher.
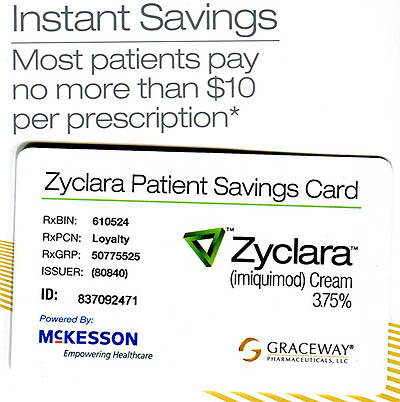
But I’ll still be annoyed that I’m paying $1,000 and most patients a lot less. My dermatologist gave me this wonderful cents-off coupon. Read the words:
Nice email: Pam emails
I am still pretty well diversified in the market and I am over 50% cash. I bought my husband a brand new car with my first batch of Apple stock, the second batch I bought two used cars for the teenagers, and I still have one more batch of long Apple and I plan to buy back AAPL after the sell off in November because their new products are exceptional and there is no competitor that can even touch their product for a long time..
I had the same scenario happen with Microsoft years back.they had a pretty good 10 year cycle. My husband and I have been very frugal and smart, we almost own our home, have absolutely no debt, my daughter got a full college scholarship, son’s starting at community college. I always make sure that I pull some money out for enjoyment, but I STILL ALWAYS HAVE THE NEW ENGLAND FRUGAL HAT ON. AND we always manage our own money and take your advice “if its too good to be true it is”.
Magazines are desperate. Desparation leads to dishonesty. Item:
The New Yorker sent me an “about-to-expire renewal” email. Cost $69.95 for one year. I was curious. I went to www.NewYorker.com. A one year subscription is $39.95. Two years is $69.95.
If I sign up, there’s this tiny type, “Subscribers’ Automatic Renewal Feature: My magazine subscription will be automatically renewed each year unless I tell you to stop. 2 months before each new subscription term, I will receive a reminder notice highlighting the renewal rate then in effect. If I do nothing, my credit card will be charged or I will receive an invoice for another subscription year. I may cancel by calling 1-800-405-8085 begin_of_the_skype_highlighting 1-800-405-8085 end_of_the_skype_highlighting at any time during my subscription or up to one year after the address is considered undeliverable, and receive a full refund on any unmailed issues.”
My present subscription doesn’t expire until November 22. That’s in even tinier type.
What’s irksome: I really like the magazine. I hate them playing games with my brain.
A bargain at twice the price. Chopard has chosen to mark its 150th anniversary by creating the most complicated watch in its history.
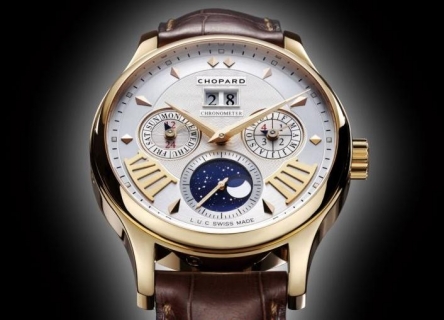
This mechanical monster features four winding barrels, 516 parts and 42 jewels. The case houses dials for hours, minutes, small seconds, a perpetual calendar, and 24-hour indicator. Turning the watch over (I don’t have a photo) reveals a secondary set of indicators that show equation of time (whatever that is), power reserve, sunrise and sunset times, an orbital moon phase display and whether it is day or night (most useful if you live in a cave). The watch delivers less accurate time than my $15 quartz Timex, but it requires regular, expensive maintenance. The cost is only $300,000.
Aw shucks. To the rescue …
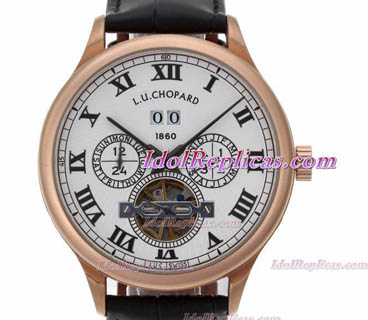
This fake one only costs $113. Click here. Use this one to impress your friends. And your Timex to tell the time.
What am I?
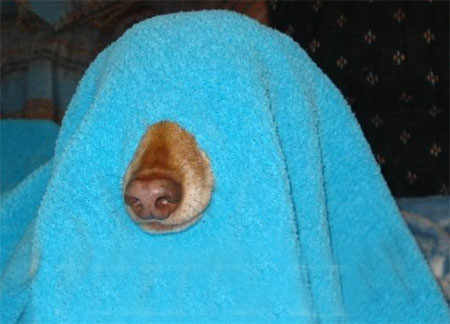
I’m a guide dog for someone wearing a Burqa.
I know this is stupid. But I found it funny. I’m weird.

Harry Newton who has added two stocks to the recommended list — GOOG and CAT. I looked at ARMH. I like its story. Chip maker to the mobile business. But it’s become very pricey — Something like 70+ P/E.

What's your take on Bill Maher's New Rule: “The next rich person who publicly complains about being vilified by the Obama administration must be publicly vilified by the Obama administration.”?
Full text at— http://www.huffingtonpost.com/bill-maher/new-rule-rich-people-who-_b_737429.html
Not being rich I thought it was a refreshing point of view… where does the truth lie?
Harry:
I'm quite sure Tepper has made 40% per year. But what about his clients?
In his remarks this morning — boiling it down — he was basically saying that equities can only go up.
Really?
Have we already forgotten Japan and its endless intervention and QE?
Have we already forgotten the Nasdaq — STILL less than half of what it was 10 years ago?
And as for the S&P being very cheap vis a vis future earnings, its well known that in the process of analysts “selling their book” that they are overly optimistic most of the time.
Don't know about you, but I can't pull up next year's earnings in MY crystal ball.
And could it just possibly be, that Tepper is “selling his own book”?
I know he wants everyone to benefit from his altruistic advice, but is it even remotely possible that
he's doing some selling, having gotten on TV?
What people say on CNBC and what they do are never checked for consistency. Never believe anyone except yourself. Meantime, keep your stops tight.
Have you asked your Doctor for a few samples of the magic medicine to see if it works, before you invest $1,000. ?
After much garfuffle, I ended with a generic version for $302. Go figure.
Why would anyone waste money buying watches anymore with PDAs, phones, IPODs, etc., all flashing the time?
I have a lightweight $15 Timex which I wear occasionally. It's often easier than dragging out my iPhone.
Is TBT supposed to be the reverse of TLT? Then it should bet on interest rates rising …
TBT goes up when interest rates rise and vice versa.