Butterfly iQ is a handheld ultrasound imaging device that connects to an iPhone or Android phone and shows your innards on the phone — and what’s right or wrong with them.
This thing could save your life. It could diagnose your ailments long before conventional (and expensive) diagnostic tools — and at far lower cost. And do it right in your doctor’s office.
It can show your heart valves opening and closing and detect any problems. It can cut heart attacks. I’ve had three friends who’ve had one recently.
If Butterfly iQ works as well as it seems to, it could absolutely revolutionize your and my healthcare. Improve it. Find ailments in advance. Cheapen our health bills. And keep me alive longer (though not a benefit, according to some of my readers).
I am unbelievably excited. But — a caveat — I haven’t seen or used the device. I’ll report on it after my wonderful doctor, Jerry Clements, has used it on me and his other patients.
Here’s what it looks like, courtesy Popular Science magazine:
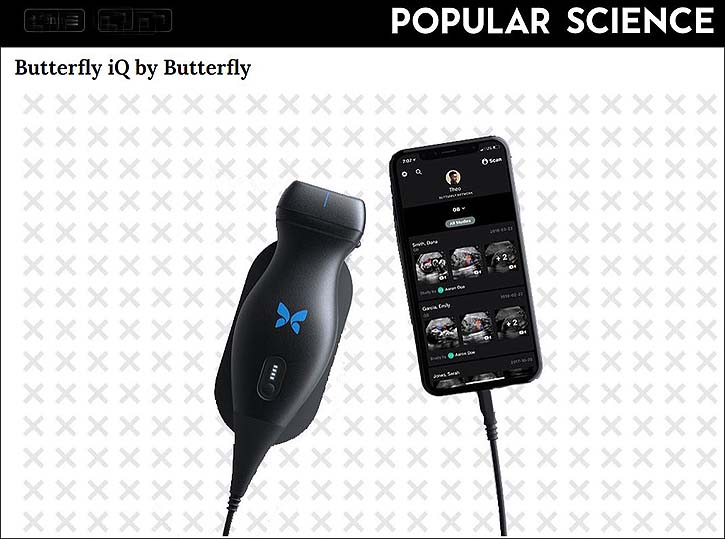
Here’s what Popular Science wrote:
Ultrasounds for everyone
Ultrasounds are incredibly useful: They allow physicians to visualize our internal organs, muscles, tendons, and even the blood vessels in our hearts. But the machines are also cumbersome and expensive. Costly piezoelectric crystals must be carefully incorporated into each probe, and different areas of the body require their own probes; a high-frequency ultrasound reaches shallow tissue just under the skin, while a low-frequency one visualizes tissue deep under the skin, like the heart muscle. The Butterfly iQ is different. Instead of a piezo crystal, the device uses a far cheaper silicon chip that can generate frequencies needed for any depth. This reduces the cost of an ultrasound machine from $40,000 or more to just $2,000, putting the purchase within reach of more physicians.
FastCompany wrote:
Because of its ability to revolutionize both U.S. healthcare and frontline healthcare in the developing world, interest in the tech is high from a wide variety of investors. In 2018, Butterfly iQ received $250 million in funding from Fidelity, the Bill & Melinda Gates Foundation, York Capital Management founder Jamie Dinan, and Fosun Pharma. Last fall, the company began shipping to more than 20,000 medical professionals who reserved devices in advance.
For the FastCompany piece, click here.
Business Insider wrote a piece headlined:
A startup that makes a new iPhone ultrasound device, whose chief medical officer used it to diagnose his own cancer, just raised $250 million. …
Ultrasound is the safest and most widely used medical imaging equipment. It is used for medical imaging inside the body and can detect the presence of anything from blood flow, to tumors, to unborn babies.
“In almost every single disease state, there’s a role for ultrasound. It has incredible versatility,” chief medical officer Dr. John Martin told Business Insider. It’s been in use since the 1950s, but cost has made the equipment extremely prohibitive.
Initially, these machines ran up to a price tag of over $100,000. Now, the average ultrasound costs about $60,000-$80,000. Add that to the fact that you needed medical specialists with the expertise to capture and interpret the image.
“We wanted to make it cheaper, easier to capture the image, easier to interpret the image so it can become available, not only to every healthcare provider in this country, but to address the issue that two-thirds of the world right now has no access to medical imaging,” Martin said.
For the Business Insider story, click here.
Here are two videos which will tell you more:
Here’s a video a kind reader, Joe Hollenkamp of Chicago sent me.
Butterfly web site is here.
I’m still obsessed with leaf-peeping
Yesterday in Columbia County, New York — about 127 miles north of New York City.
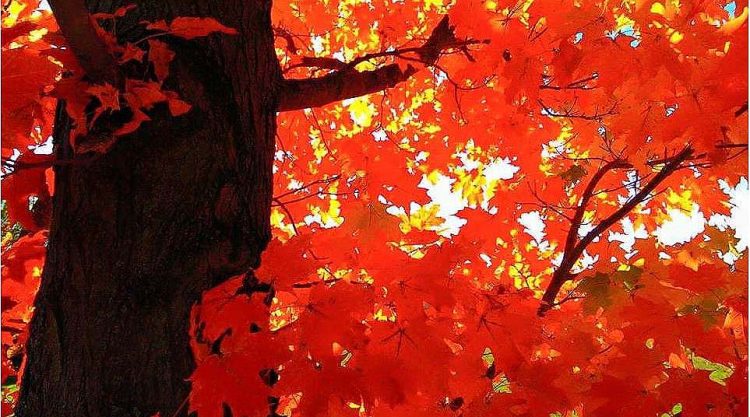
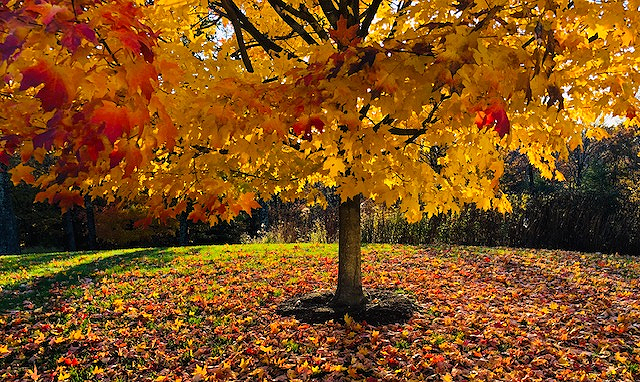
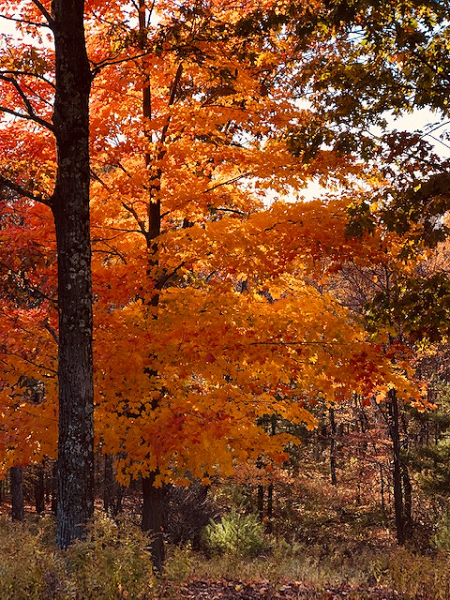
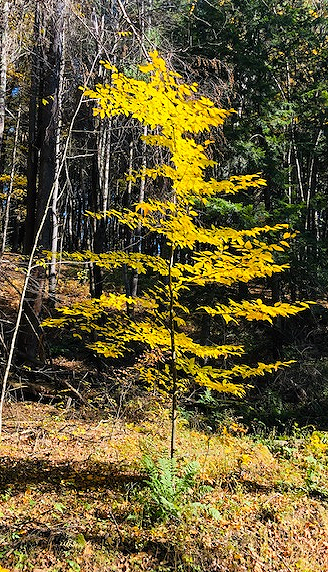
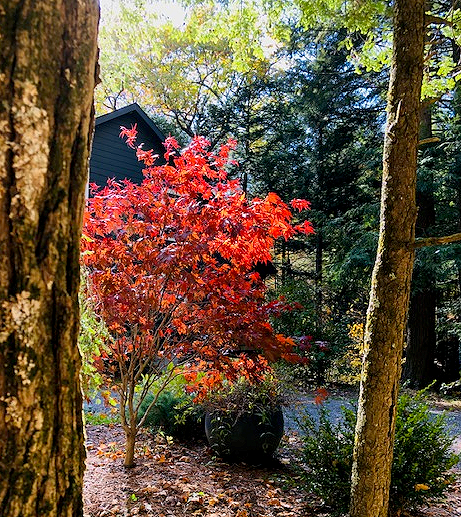
I’m pinching myself with my good luck, playing tennis outdoors late October. This is a joy. This weather will keep up today Friday and Saturday. Then rain on Sunday. Get up here quick.
Vermont is peaking in the south of the state. Click here.
I sold TWLO yesterday. That was really dumb. BA went up. I’m short. That was also dumb, so far.
However, my BX buy is doing good. And PYPL, MRVL, FTNT, DOCU, ADBE and BIIB are up nicely.
Not too happy about Amazon. I should have sold it when it hit $2,000. Good lesson: Always take a chunk off the table when Mr. Market gives us a ridiculous price.
I don’t own FB, though my friends tell me it’s a fantastic vehicle to advertise their stuff. I worry about the politics/regulation, etc. For more on that, read Rolling Stone’s latest piece:
What Alexandria Ocasio-Cortez Exposed About Mark Zuckerberg and Facebook Heading Into 2020
Facebook isn’t only tolerating disinformation in political advertisements, it’s facilitating it
Mark Zuckerberg is an awkward guy. This is true when he’s giving tours of his house, it’s true when he’s live-streaming himself smoking meats, and it’s especially true whenever Congress is grilling him about how the social media network he created to keep tabs on the relationship status of his crush is facilitating the downfall of Western civilization.
Such was the case Wednesday, when the Facebook CEO was confronted by Rep. Alexandria Ocasio-Cortez, who has already proven herself to be one of the sharpest, most effective inquisitors in the House. And the exchange revealed a core truth about Zuckerberg as he struggles to reckon with how Facebook has been used to subvert democracy:
He has no idea what he’s doing.
You can read the full Rolling Stone article here.

I watched the clip of AOC “grilling” Zuck several times. I’m no fan of Zuck or FB but every so-called question was of the form “Do you still beat your wife?” I’d bet a lot of his “awkwardness” has him trying to restrain himself from telling AOC where she could shove her questions.
My friend and yours, Mr. Toby Bugfoot, lives in Columbia County.
Harry, I have read your blog for years. You rock. That is all. Ron
Harry…you like DQ hamburgers…I too have enjoyed them over the years. However, not having a taste for the ubiquitous cardboard quarter pounders I have not had a good hamburger for some time. I finally found one! Give Fuddruckers a try…Lorette and I shared a really great hamburger the other day…the Fuddruckers ONE POUNDER! Yes, it was filling and yes it was delicious cooked to order. Nearest one to you appears to be 3159 Route 46 E,Parsippany, NJ https://www.fuddruckers.com
I think amazon is worth averaging into here and holding longer term. Here is what one of my favorite managers wrote at realmoney.com about it this morning: Oct 25, 2019 | 09:43 AM EDT DOUG KASS
Amazon Is a Deal
* Though guidance was weaker than expected, Amazon is putting more distance between it and its competitors
* I continue to expect a “hockey stick” improvement in profits and cash flow two years out
* After slashing my position at much higher prices prior to the EPS release, I began to add back at $1637-$1640 in the after hours
* My year-end 2020 price target is $2000-$2300
Amazon (AMZN) beat on the top line ($70 billion vs. consensus of $68 billion, +24% which was +300 bps better than the previous quarter) and bottom line but guided lower for 4Q2019.
E-commerce accelerated. Higher margin advertising sales also accelerated. Other revenue did as well (in rate of growth terms, +45% year over year and +8% quarter over quarter). AWS sales growth of +35% (about $150 million below consensus) dropped from +37% in 2Q2019 – the fifth consecutive quarterly slowdown in the growth rate. (But, put into perspective, the AWS add of $9.3 billion is larger than Microsoft’s (MSFT) Azure and Alphabet’s (GOOGL) Google cloud combined. Moreover, future commitments indicate a long runway lies ahead.)
The conference call suggested that Japan sales were pushed forward due to a scheduled consumption tax hike and to a Diwali Holiday shift in India.
The important metrics of absolute unit growth and an acceleration of sales delivered by 1-Day Prime were intact.
Forward guidance was weak (margins were projected to drop by 70 bps, the first drop in a decade) – reflecting, among other things, rising shipping and fulfillment costs (one day Prime shipping), higher personnel and marketing expenses (AWS) and a slightly weaker than expected Holiday season. I would not be surprised to see the company beat these conservative forecasts.
Importantly, based on our analysis, we don’t consider these investments as permanently increasing the company’s cost structure and long term profitability.
Though higher than expected, we must recognize that this will serve to put more daylight between Amazon and its competitors – it’s this deepening moat that underscores the fundamental reason why I still expect Amazon to become the first $2.5 trillion company:
In the annals of U.S. corporate history there is no company that has as large and lengthy a runway of opportunity as Amazon.
It is that prism of opportunity that supports my strong belief that Amazon’s earnings growth will far exceed consensus expectations.
Here are the five keys to my increasingly bullish case:
Amazon’s first-mover advantage is now impenetrable; the company no longer can be caught by its competitors.
Amazon’s broad product offerings and technological advantages no longer can be duplicated.
On the wings of a nearly zero cost of capital Amazon has expended enormous sums of capital to produce the massive and insurmountable competitive advantage that exists today. That “kindness of strangers”in such scale likely will never be duplicated again by a competing business entity, thus placing Amazon light years ahead of its competition. Indeed, in this marathon of disruptive growth (a marathon approximates 26.2 miles), Amazon is at least 20 miles ahead of its closest competitor.
Based on my company analysis, Amazon is about two years away from “hockey stick” earnings-per-share (EPS) growth that will far exceed consensus expectations. The source of my profit optimism and above-consensus growth projections are several fold, but are keyed on an expansion in operating leverage and profit margins produced by a lower rate of growth in expenses and higher top-line results. The latter will be aided by continued above-expected core retail sales gains and the anticipated success in the company’s high-margin advertising initiative as well as other emerging businesses.
Based on our EPS model I am more optimistic than the consensus regarding the assumptions of top- and bottom- line growth over the next five years. 2021 is the year when the largest gain relative to expectations is projected. With more than one quarter of this year already in the rear-view mirror, it is not too early to consider results out two years.
Returns for Amazon Shareholders Will Likely Come in The Second Half of 2020
As noted recently, I now believe that the next six months will be a challenge to social media stocks like Amazon – that is why I reduced my holdings from very large to between small and medium several days ago.
“It is now clear that to this observer that the bull market in the larger social media stocks may be delayed, reflecting a clear inflection point in greater potential legal, legislative and regulatory disruption towards the social media companies. These changes and pressures are likely to multiply as we approach the November 2020 election – as how to deal with “surveillance capitalism” becomes one of the primary policy positions of the Democratic party.”
Bottom Line
After having sold a lot of stock recently (at much higher levels), I began to reestablish a larger position in the after hours yesterday (at $1637-$1640).
Amazon now trades at under 20x 2020 EBITDA. The stock trades at less than half the average across the large cap tech universe (0.6x 2020E EV/EBITDA to growth compared to 1.3x the large cap average) – compelling especially in light of the prospects for future upside profit.
I expect, by year-end 2020, that Amazon’s shares will trade between $2,000-$2,300 as investors begin to recognize that a “hockey stick” acceleration in EPS and in cash flow, and a faster pace of margin expansion (as it grows into a larger infrastructure) lies ahead in 2021-22.
Position: Long AMZN
The Butterfly iQ looks to be phenomenal…I am scheduled for my annual physical in a week and I will most certainly talk with my doctor about it….I have had several ultrasound scans that cost me and my insurance company money…sure hope this works out as well as anticipated.Thanks for sharing.
Your fall pics are very beautiful…having lived in New England for a number of years we really appreciate them…we only have the golden Aspen here in AZ. If you really want to experience fall color tour the UP in Michigan some time…it can beatout New England some years.
Send your doctor my piece now. By the time you visit him he may have one and you can be a guinea pig.