Fidelity rips its customers off with misleading software: The story: A talented friend takes over a mutual fund. I figure I’ll buy a little. I spend $25,000. When I check my Fidelity online the next day, it shows I’m down $1,438.44 on that purchase. How can that be?
Turns out that Fidelity and the fund had charged me a 5.75% front end load, which I believe Fidelity did not adequately disclose.
I call Fidelity yesterday, asked what happened. They explained the fee. I say I wanted the transaction reversed on the basis of their misleading and inadequate disclosure. They tell me — in no uncertain and in extremely unpleasant tones — to go pound sand. In other words, “Get lost.” Take my business elsewhere.
There are several lessons here:
1. There are always fees. That’s why Wall Street is in business — to collect fees. It loves fees.
2. CHECK. CHECK. CHECK.
3. Don’t believe most everything your on-line broker tells you. Before I hit the button that said “Place Order,” this is the screen that Fidelity gave me yesterday. So where are the fees?
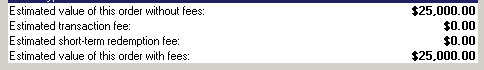
Nicely hidden and totally disguised.
Paving Path to Fraud on Wall Street. The return of the Rip-Off Factor on Wall Street.
Just days before Greg Smith publicly criticized Goldman Sachs, a bill removing safeguards for investors sailed through the House. It is now on the floor of the Senate.
Read today’s New York Times.
Something is happening to long-term interest rates. A reader sent me this chart late yesterday:
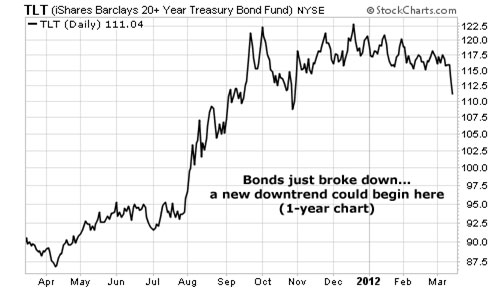
TBT is moving up. Finally.
Latest “brilliant” computer fix-it ideas:
1. Turn off the annoying sounds Windows makes when it starts and shuts down. Go into Control Panel / Sounds / Sounds and choose the “sound scheme” called No Sounds. This works in all versions of Windows. My new, quiet computers are a bliss.
2. I’m still using Office 2003 . I poll my kids how they like Office 2010, which their companies had foisted on them. Universal answer: NO. They hated it. Few new benefits, no faster searching and a huge amount of wasted time learning new places for dong old things. Or as Claire wrote, “It was so annoying learning the new places Microsoft hid functions.” They call agreed “change is usually bad with software.” In short, if it works, don’t mess with it. And don’t upgrade unless you’ve tested the new upgrade and you can see the benefits of newness.
3. My second screen (the external Toshiba one) conked out — because I had unplugged the screen and taken the laptop traveling. Only way to fix it? Reinstall the Displaylink drivers. Re-installing software and hardware drivers is typically a lot faster than trying to figure out what went wrong and coax them back into action.
4. Every so often, I think I should “upgrade” from Windows XP and Windows 7. And every time I try, I end up asking myself, “What did I gain?” Speed? Reliability? Ease of use? And the answer, once again, is “None of the above.” Fortunately I only experiment with new software on my “test” computers — not the ones I use for real work. I continue to marvel at the arrogance of software companies who destroy perfectly fine software with their “new” ideas. In the trade it’s called “feature creep.” To me, it’s just plain arrogance. And Microsoft is the absolute worst, despite their stock having risen recently.
5. If you’re using Win 7, however, do use the 64-bit version. You’ll get the ability to access much more than XP’s tiny 3 gigabytes of RAM memory. I’m playing with a new ThinkPad X220 which has 8 gigs of RAM memory. The problem with 64-bit operating systems is much old software doesn’t work. For example, my favorite, old synchng software called FileSync doesn’t work. But Microsoft’s free SyncToy 2.1 does. Microsoft describes SyncToy as:
SyncToy 2.1 is a free application that synchronizes files and folders between locations. Typical uses include sharing files, such as photos, with other computers and creating backup copies of files and folders.
Pick up a copy here.
Lean Times for Dewey & LeBoeuf.
Fascinating story of a mammoth legal merger gone all wrong. Read the New York Times story here.
How to retire in style
“I have enough money to last me the rest of my life, unless I need to buy something.” — Jackie Mason
Wonderful iPad video. The German video shows a father who has received an iPad as a gift from his daughter. She is asking him whether he likes his new ‘toy’ and he then …. well, wait till you see. You’ll die laughing. Click here.
Latest favorite “joke.”
Two women were for a stroll. One had a Doberman and the other, a Chihuahua . As they walked down the street, the one with the Doberman said to her friend, “Let’s go over to that bar for a drink.”
The lady with the Chihuahua said, “We can’t go in there. We’ve got dogs with us.”
The one with the Doberman said, “Just watch, and do as I do.”
They walked over to the bar and the one with the Doberman put on a pair of dark glasses and started to walk in.
The bouncer at the door said, “Sorry, lady, no pets allowed.”
The woman with the Doberman said, “You don’t understand. This is my seeing-eye dog.”
The bouncer said, “A Doberman?”
The woman said, “Yes, they’re using them now. They’re very good.”
The bouncer said, “OK, come on in.”
The lady with the Chihuahua thought that convincing him that a Chihuahua was a seeing-eye dog may be a bit more difficult, but thought,”What the heck,” so she put on her dark glasses and started to walk in.
Once again the bouncer said, “Sorry, lady, no pets allowed.” The woman said, “You don’t understand. This is my seeing-eye dog”
The bouncer said, “A Chihuahua?”
The woman replied: “A Chihuahua ? They gave me a Chihuahua?”

Harry Newton who notes the new iPad goes on sale today. Steal yourself for yet more photos of happy Apple fans lining up outside Apple retail stores in hopes of snaring one. TaskRabbit even sent out a mass email yesterday,
“Get the latest iPad without the hassle. Hire a TaskRabbit to wait in line for you to get your hands on the latest Apple phenom!”
TaskRabbit is one of the more brilliant startups of recent years. Should you need something done, you post the task and how much you’re willing to pay. One or several local “taskrabbits” will respond. Bingo, your problem solved.
Daughter Claire, a busy, successful lawyer, uses TaskRabbit all the time. Example: She and husband Ted recently flew from Boston to Portland, Oregon for son Michael’s surprise 30th birthday. She had TaskRabbit pick them up at Portland Airport with a bunch of “Happy Birthday” helium balloons and drive them to Michael’s house. The adventure went off perfectly, though they did get a little lost on the way to Michael’s Mansion. Cost $60. No extra charge for the tour. TaskRabbit checks all its people out before allowing them to become TaskRabbits. To use TaskRabbit, click here.
UBS upped its price target for Apple from $550 to $675. Apple closed last night at $588.81. Walt Mossberg at the Wall Street Journal reviewed the new iPad favorably. Click here.
The finals of the Indian Wells Tennis are on this weekend. Check out the Tennis Channel and ESPN.

WOW! A lot of hating here today. What gives? I do not use Fidelity but the image Harry has on here clearly shows that there are no fees attached to this order. Perhaps it says a lot about Wall Street that we are to assume that we will be facing fees/load when buying into mutual funds unless it is clearly indicated that the fund has no load. Kind of like trying to assume a party is guilty until he/she proves him/herself innocent. What a shame.
Harry, Fidelity is beyond reproach. I have dealt with them for 20 years without a problem. You were stupid. Stop with placing the trades online. Just pick up the phone and call them for god's sake and ask if there's a fee. (99% of their funds are pure no load.)
Also, I know of one of your children, I won't say who. This offspring is considered an even bigger idiot than you. So stop bragging about your kids. They're morons too.
I laughed outloud at the dog joke. Thanks
PAVING THE WAY TO FRAUD ON WALL STREET–The return of the Rip-Off Factor on Wall Street. First we get the lies from the New York Times so I thought I'de provide the TRUTH. Enjoy……
http://campaign2012.washington…
Harry, if you're going to wrestle with pigs you'll get dirty and the pigs will enjoy it. Why not take time to obtain an RIA license (it's really not that hard), do your own investing through a low-cost independent source, and leave the pig pens behind?
When playing Poker, one of the basic rules is this: If you look around the table, and cannot figure out who the Patsy is, you are likely the Patsy.
In yesterday's column you showcased Greg Smith's Letter to the New York Times in which, as an insider and Partner, he announced his resignation and condemned the firm's practices towards its very own clients. They called their clients “Muppets”, had a disdain for them on an interpersonal level, and placed them in high-priced and often big-fee items. Clients tended to stay because they accepted this boorish behavior so that presumably they could brag at their East Side cocktail parties that they were within the Goldman fold. While what Goldman does is clearly a Rip-Off, though not illegal, the clients seem to enjoy their role as Patsy.
You state in your column that you are “a client of Goldman”. You state “Im not impressed with their client-pleasing skills”. You state “theyve made more in fees from me than theyve ever made for me”. You state “they have treated me poorly”. You state that “if I had a choice, ie I would sell the funds I have with them at what I paid for them eons ago”.
In every way, Goldman has failed you in your own words, but still you stay.
Goldman Sachs was at one time a great firm, and it was indeed an honor to have monies with them. Perhaps one day they will rise from the stink, and retake that mantle.
On Wall Street, the best way to reward is to keep your monies and add to same with a broker/firm. THe best way and the only way Wall Street understands bad behavior including service and fees, is to Punish via Withdrawing Funds.
THere are probably 10,000 brokers and 500 firms that would love to have your money, but you persist in keeping it with those who you acknowledge treat you in every way poorly.
Imagine if you and everyone like you withdrew your monies, not for Greg Smith's column, but because Goldman had merely failed to treat you like a valued client, and not a Patsy. In the aggregate, Goldman would likely get the message.
Your money is your money, Goldman can liquidate it every day if you give them the order to do so. You keep it there waiting for the day you break-even. Meantime you bitch and moan.
C'mon man, use the same Courage you use to get into a match on your beloved tennis courts.
Stand up straight, look em in the eye, tell them you've had enough, and Stop being the Patsy.
My money with Goldman is in two Goldman funds — one a hedge fund of distressed hedge funds and the other a private equity fund. To liquidate either holding would involve a huge haircut — probably 50%. Both funds are eeking their way back, despite the huge fees to Goldman. It makes sense to stay.
C'mon Harry, the simple Coca Colas and Caterpillars (not very sexy) are making new highs every day as the market is at 4 year highs. Private equity down 50%, they really have to work to accomplish that. And a hedge fund of distressed hedge funds is like taking a collection of various dog poos from Central Park and calling it cotton candy: its still a collection of distress.
Dont complain; this wasnt SOLD, it was BOUGHT. Move on.
Harry – grow up! We are getting tired of your rants and raves about your multitusde of accounts at brokerage firms you do not like. Yesterday Goldman now today you have a problem with Fidelity. I have been a customer of Fidelity for years. Their website is very easy to use and for more sophisticated investors/traders they have an upgraded platform. Fidelity is first and formeost a mutual fund company. They ave very easy to use and navigate information sections that outline in plain English the associated fees and commissions for each and every mutual fund. It takes about a minute to get this information for a mutual fund you were about to buy. You clearly didnt take the time to get the information and now you blame Fidelity. I bet you did this in haste and did not take the few minutes needed to get the fee information relative the the fund you bought. It is all there. Full disclosure is mandated by law and all the information you need and want is right there had you taken a minute or 2 to get it. grow up!
Look at the image of what Fidelity returned to me.
There's absolutely no mention of front-end fees – or any fees. The clip is black and white.
If anything, Fidelity deliberately mislead me.
should I have assumed that they were going to mislead me?
Yes!!! And that was my fault for my not assuming their dishonesty.
Harry – for a sophisticated guy you really have no clue. The clip you provide is the window that pops up when you are about to place an oder or trade. Those “fees” generally refer to commissions or transaction fees like SEC, FINRA fees. You were buying a mutual fund and funds have “load or no-load” fee structures. That information is easily and readily available by simply clicking the mutual fund you were about to purchase and all the info comes up. Clearly you bought a fund without even doing your homework. Had you simply looked up the fund on the Fidelity website it would have given you al the fee info you needed. It would have given you a symbol for the fund and you could have clicked the symbol for additional info and fee info. The lesson is that beforw you place an order you should know what you are buying and the associated costs. Had you just bought a stock the window (image) returned to you would have had a commission listed but because it was a mutual fund there is an imbedded or implied load (or no load). I guess you are not as sophisticated as you would have us believe. I have been using Fidelity platform and just upgraded to Fidelity Trader P{ro – it's great. You just need to take a few minutes to understand how it works before you go placing orders and tarding…duuhhh!!
I'm with Harry on this.
Where's the little asterisk next to the “Estimated value of this order with fees:”
Right there is should have, at a minimum, disclosed (excluding front-end loading fees). The word fee and loading might have different meaning but they do the same thing — reduce the amount of funds that you have available.
And any company that purposely omits that little detail deserves any mud slung at them.
I laughed out loud at the iPad video.