The SEC’s civil fraud case against Goldman Sachs is not complex. It asserts Goldman made “materially misleading statements and omissions with a synthetic collaterialized debt obligation (“CDO”) GS&Co structured and marketed to investors.” In particular Goldman forgot to tell its buyers that a large hedge fund, Paulson & Co. Inc. “with economic interests directly adverse to investors in the ABACUS 2007-ACI CDO, played a significant role in the portfolio selection process.”
After selecting the portfolio, Paulson shorted it. The Paulson fund made $1 billion. The investors whom Goldman sold the CDO to lost $1 billion.
Goldman will argue that its marketing materials for ABACUS made oodles of representations that no one should rely on anything Goldman was telling them verbally or in writing — like all Wall Street I banks and brokerage houses do. Caveat emptor. Buyer beware.
There was, however, one thing different about this. John Paulson had handpicked the mortgages because he knew they were crap. Goldman obviously concerned about their quality and had dragged in (and paid) a company called ACA Capital to pretend it chose the mortgages and to put its seal of approval on the deal.
This is conniving, but probably not illegal.
There are obvious lessons (none of which are new, but there are some new wrinkles).
1. Once upon a time investment bankers focused on their clients. They created financial products for them. They managed their money. In its defense, Goldman Sachs says it always puts its clients first. This is simply not true. I have an investment in a Goldman Sachs private equity fund, which is presently under water (i.e. losing money). I recently paid a large capital call. Much of that capital call did not go to buying new, potentially-lucrative investments. They went to paying off Goldman’s accrued management fees.
In recent years, as the Wall Street Journal pointed out on the weekend, Goldman Sachs “has seemingly shifted from a strictly client-focused firm toward a trading house where the line between clients and counterparties is blurred.”
In short, when you buy an “investment” from them, you no longer know where you stand. I rue and regret the investments I have with them.
2. For God’s sake don’t buy something you can’t understand. This ABACUS deal was a “synthetic collateralized debt obligation (CDO)” I think I understand what it was, maybe. Goldman created a 66-page PowerPoint deck to help explain the deal. My favorite slide is page 50:

3. Wall Street does a lousy job figuring where things are going — despite all their “research.” Their BIG assumption is that the future will look like the past. With three huge financial busts in the past ten years, you can no longer make this assumption.
4. Goldman received a bunch of Wells notices from the SEC in recent months. It didn’t o tell its shareholders that the SEC was investigating the company! (Go figure.) Goldman chairman and CEO Blankfein told Congress recently he “was doing God’s work.”
This is getting weirder and weirder.
For the SEC’s 20-page accusation against Goldman, click here. I’ve highlighted the important bits.
For Goldman’s own PowerPoint deck, click here.
You need to read these two documents before you read what reporters, like Matt Taibbi of Rolling Stone are saying. From Taibbi:
Goldman, Sachs is getting busted, finally, for what to me is one of the most devious and brilliant crimes of the last decade.
I can’t get into this too much because I have other material coming out about it. But the upshot of it is that GS teamed up with a hedgie named John Paulson (no relation) to make the biggest ball of subprime shit they could, got short of it by credit-default-swapping it, then roped third parties into buying it. It’s kind of awesome in a way, and I’m sure it was fun while it lasted.
But now I’m reminded of the scene in Goodfellas when the cops bust Henry :
Bye bye, dickhead!
I have no idea how Goldman, the SEC and all the financial pontifications will affect this market. Is suspect they won’t be good. But I’m not “buying on the dips.” The market has looked like it’s needed a little pullback for some time.
Citigroup reports a nice profit this morning. I’s reading Citi’s 272-page annual report for 2009. I repeat 272 pages of tiny print, no pictures and lots of unanswered questions.
Much worse than Goldman Sachs is today’s hay fever. Allegy season is on us with a vengeance. The solution is twofold:
+ Wash your face with cold water, and
+ Claritin.
The world’s most expensive coffee beans are found in the droppings of the civet, a catlike animal from Southeast Asia, whose digestive tract produces a smooth brew.
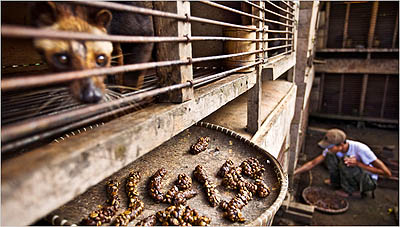
A civet farm in Liwa, a town in Sumatra, where the catlike animals eat coffee cherries. Their droppings contain coffee beans fermented in their stomachs. Learn more.
Friday’s column exists. It was late because Time Warner’s RoadRunner was “losing packets.” Meantime, you can read it by clicking on the date above and then clicking on the headline, to bring up the full column, which had some funny cartoons.
Driving Miss Daisy. A friend, who worked away from home all week, always made a special effort with his family on the weekends. Every Sunday morning he would take his 7-year old granddaughter out for a drive in the car for some bonding time — just him and his granddaughter. One particular Sunday however, he had a bad cold and really didn’t feel like being up at all. Luckily, his wife came to the rescue and said that she would take their granddaughter out.
When they returned, the little girl anxiously ran upstairs to see her Grandfather.
‘Well, did you enjoy your ride with grandma?’
‘Oh yes, Papa’ the girl replied, ‘and do you know what? We didn’t see a single ass hole, dumb bastard, dip shit or horse’s ass anywhere we went today!’
Almost brings a tear to your eye?
Harry Newton, who’s amazed at how much time he wasted reading on the weekend all the “news” about Goldman Sachs. There really isn’t that much to understand. I’m betting Goldman will settle, pay a small fine, and plead the usual “we don’t admit any guilt.”

Harry, with all due respect I disagree with your dismissal of the Goldman situation with the usual “caveat emptor” approach of “it ain't illegal”. First of all, they didn't disclose a critical piece of information: how can you as a buy “beware” of what you cannot know? Second, the old legal cop-out: precious little would be punished if you just play legal word games with attorneys. There has to be a consensus common sense standard applied. Fraud is fraud.
Harry, why did you have to pay the Goldman capital call? Wouldn't you qualify this as a 15% stop-loss situation? Is there a large penalty for withdrawing? Having never invested with an I-bank I would be curious to know some of the rules.