Get yourself a powerful computer. Feed it all the stockmarket trades that are happening and/or about to happen. Program the computer with rules: One might be: If there’s a big order for a stock, buy it. If there’s a big order or orders to sell the stock, pound it.
Computers can sell and buy stocks faster than you and I. Computers are “rational,” depending on who programmed them. But they’re not human. Which means they may do stupid things — like exacerbate volatility — viz. last Thursday week.
Computers are stacking the stockmarket playing field against you and I. They’re faster. And they have much better information. I’d call it insider information. That information allows them to front run your and my orders. Front running is illegal. But it’s also fattening.
All this is called high frequency trading. HFT. And it accounts for a whopping two-thirds plus of daily volume on ALL stock exchanges, including NYSE and NASDAQ.
I don’t know what the full implications of HFT are. I’m still learning. The major ones:
+ There will be more volatility and more deeper volatility. That means you have to be very careful of your inviolate stop loss orders. You don’t want to be holding P&G to find you suddenly got stopped out at a 40% loss. And then half an hour, it’s back, way above what you sold it.
+ Youcannot have automatic stop losses ones any longer. You have to have manual ones, i.e. trigger them yourself.
+ Don’t even think about day trading. You cannot compete against the machines. Trust me. You cannot.
This is from Wikipedia’s definition of algorithmic trading:
In electronic financial markets, algorithmic trading or automated trading, also known as algo trading, black-box trading or robo trading, is the use of computer programs for entering trading orders with the computer algorithm deciding on aspects of the order such as the timing, price, or quantity of the order, or in many cases initiating the order without human intervention. Algorithmic Trading is widely used by pension funds, mutual funds, and other buy side (investor driven) institutional traders, to divide large trades into several smaller trades in order to manage market impact, and risk.[1][2] Sell side traders, such as market makers and some hedge funds, provide liquidity to the market, generating and executing orders automatically. A special class of algorithmic trading is “high-frequency trading” (HFT), in which computers make elaborate decisions to initiate orders based on information that is received electronically, before human traders are capable of processing the information they observe, in addition to which they can reduce costs of trading and improve shareholder returns.[citation needed]
Algorithmic trading may be used in any investment strategy, including market making, inter-market spreading, arbitrage, or pure speculation (including trend following). The investment decision and implementation may be augmented at any stage with algorithmic support or may operate completely automatically (“on auto-pilot”).
A third of all EU and US stock trades in 2006 were driven by automatic programs, or algorithms, according to Boston-based financial services industry research and consulting firm Aite Group.[3] As of 2009, high frequency trading firms account for 73% of all US equity trading volume.[4]
In 2006 at the London Stock Exchange, over 40% of all orders were entered by algo traders, with 60% predicted for 2007. American markets and equity markets generally have a higher proportion of algo trades than other markets, and estimates for 2008 range as high as an 80% proportion in some markets. Foreign exchange markets also have active algo trading (about 25% of orders in 2006).[5] Futures and options markets are considered to be fairly easily integrated into algorithmic trading,[6] with about 20% of options volume expected to be computer generated by 2010.[7] Bond markets are moving toward more access to algorithmic traders.[8]
One of the main issues regarding high frequency trading is the difficulty in determining just how profitable it is. A report released in August 2009 by the TABB Group, a financial services industry research firm, estimated that the 300 securities firms and hedge funds that specialize in rapid fire algorithmic trading took in roughly $21 billion in profits in 2008[9].
Main Wikipedia article: High-frequency trading
High-frequency trading uses computers that execute trades within milliseconds, or “with extremely low latency” in the jargon of the trade. In the U.S., high-frequency trading firms represent 2.0% of the approximately 20,000 firms operating today, but account for 73.0% of all equity trading volume.[21] As of the first quarter in 2009, total assets under management for hedge funds with high frequency trading strategies were $141 billion, down about 21% from their high.[22] The high frequency strategy was first made successful by Renaissance Technologies.[23] High frequency funds started to become especially popular in 2007 and 2008.[22] Many high frequency firms say they are market makers and that the liquidity they add to the market has lowered volatility and helped narrow spreads, but unlike traditional market makers, such as specialists on the New York Stock Exchange, they have few or no regulatory requirements.
These funds are highly dependent on ultra-low latency networks. They profit by providing information, such as competing bids and offers, to their algorithms microseconds faster than their competitors.[4] The revolutionary advance in speed has led to the need for firms to have a real-time, colocated trading platform in order to benefit from implementing high frequency strategies.[4] Strategies are constantly altered to reflect the subtle changes in the market as well as to combat the threat of the strategy being reverse engineered by competitors. There is also a very strong pressure to continuously add features or improvements to a particular algorithm, such as client specific modifications and various performance enhancing changes (regarding benchmark trading performance, cost reduction for the trading firm or a range of other implementations). This is due to the evolutionary nature of algorithmic trading strategies – they must be able to adapt and trade intelligently, regardless of market conditions, which involves being flexible enough to withstand a vast array of market scenarios. As a result, a significant proportion of net revenue from firms is spent on the R&D of these autonomous trading systems.[4]
Really want to get annoyed about HFT? The HFT houses are being fed confidential data which allows them to front run. They are being fed confidential information because there are many competing exchange. They are all competing for the trading dollars. To win the business, the exchanges have to provide information to their customers. In the old days, it was computer research. These days it’s research on order flow.
Read THEMIS_TRADING_White_Paper_–_Data_Theft_On_Wall_Street_–_05-11-10
Here’s the paper’s conclusion (sorry the type is so small):

God bless English humor. Arriving for work at the U.K. Treasury last week, the incoming chief secretary, David Laws, found a note from his predecessor, Liam Byrne, summarizing England’s finances.
The note read; “Dear Chief Secretary, I’m afraid to tell you there’s no money left.”
What a wonderful weekend. This was the view from my country house on Saturday evening. That’s the Catskills in the distance.
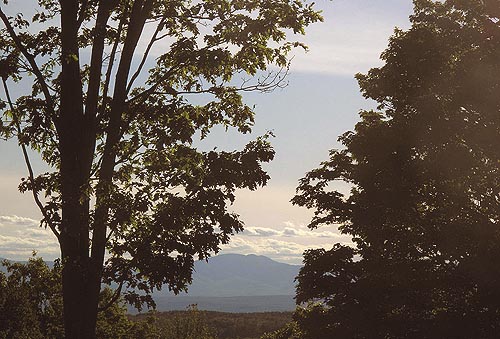
I waited and waited for the sun to turn red. But the air was clean, too clean for a deep red sunset. So I figured “Photoshop to the rescue.”
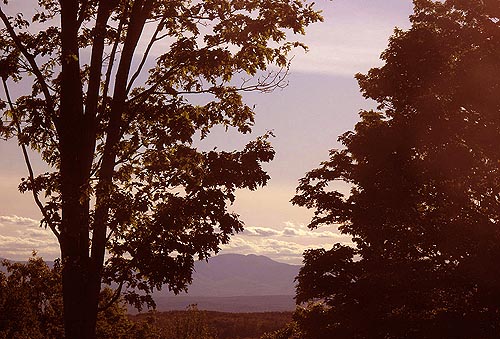
I’m not very good with Photoshop. Pick whichever reality you feel comfortable with.
Harry Newton, who continues to like gold and is looking for ward to his (increasingly) cheap vacation in France in July. I bet the Euro will fall below $1.20. But I’m not selling it short. That’s a very dangerous dame.

With all the High frequency trading going on, would it not be a good idea to put in leave orders to buy a list of shares at 30~40 % below their trading numbers in the hope that a similar drop followed by a quick recovery happens again. Given that some shares in the recent c. 1000 point dow drop fell by these margins and more but quickly recovered, there could be some significant gains to be made with limited risk (High volatility during a reasonably strong period of US economic growth should limit sustained downturn in short term at least)…. Or am I speaking rubbish as I don't really now what I am talking about?
You are 100% right. Put in orders to buy a list of stocks at 30% to 40% below the market. When your buys kick in, you'd better be around to see that you didn't just catch a falling knife.
I'm afraid retail investors are behind the curve when it comes to HFT. This is understandable. It's a complex subject and requires a reasonable grasp of “algo” strategies. What HFT is telling us, however, is that fundamentals in the classic sense no longer apply. Huge volume is generated not because of a company's solid balance sheet, strong quarterlies or favorable future guidance; instead, the company's shares are subject to programmed volume mechanics. Front running has become commonplace, and the regulators are still trying to catch up. Very few in Washington get it. My prediction: “Algo” exchanges will proliferate, stripping away traditional value in the service of presumed liquidity. Just as we have automated other industries, the traditional stock and bond exchanges are next to go. We may have find “algo” exchanges springing up overseas and operating out of dark pools. Harry is absolutely right about stop loss orders in the algo environment; investors will be forced to be hands-on, 24/7 if they hope to survive. And, at the most basic level, it's probably a good bet that your broker, your hedge fund swami, or your bond guru has little if any grasp of how all this works. And even if they did, it would make little if any difference in matters of pricing. Like most investors, they will be swimming upstream against overwhelming volatility. Should you buy? Sell? Long or short? Consult your college calculus text. HFT was a factor in the 2008. But 2008 is an eon ago in the HFT quantum mechanics realm. Today's math models are more complex and dehumanized. In the end, the question becomes: Do I really want to “invest” in this market–a market in which investment is fast becoming a quaint term of art?
Whew!