It’s time to look at shorting. Try three European banks — Deutsche Bank (DB), Credit Suisse (CS) and UBS. If you haven’t already shorted BP, that seems logical. That company is giving arrogance and incompetence whole new meanings. There is now talk on the blogs of BP actually going bust.
I’m eyeing some cheap long-term leaps. Think Nassim Taleb and the Black Swan.
Some pieces to read: From Bloomberg:
Commodities’ Biggest Drop Since Lehman Is Bear Signal (Update4)
June 1 (Bloomberg) — The biggest slump in commodities since Lehman Brothers Holdings Inc. collapsed is undermining Wall Street forecasts for accelerating economic growth and higher prices for everything from copper to crude oil.
The Journal of Commerce Industrial Price Commodity Smoothed Price Index that tracks the growth rate of steel, cattle hides, tallow and burlap plunged 57 percent in May, two years after a decline that foreshadowed the worst recession in half a century. The index of 18 industrial materials declined the most since October 2008 as Europe’s debt crisis widened and China took steps to curb growth.
Commodities extended their slump today, led by declines in industrial metals and energy prices, as separate reports showed manufacturing slowdowns last month in China, Europe and the U.S.
“As risk-taking falls, expected growth is reduced,” said Colin P. Fenton, the chief executive officer of Curium Capital Advisors LLC in Boston, who was a commodity analyst at Goldman Sachs Group Inc. and Stanley Druckenmiller’s Duquesne Capital Management LLC hedge fund. “Demand for commodities is going to be softer than it might otherwise have been.”
While the Organization for Economic Cooperation and Development raised its growth forecasts for this year and next on May 26, investors are dumping holdings at the fastest pace since February.
The Journal of Commerce Industrial Price Commodity Smoothed Price Index reflects clearer signs of supply and demand than futures markets because half the items it tracks don’t trade on exchanges used by speculators, said Lakshman Achuthan, the managing director at the New York-based Economic Cycle Research Institute. The gauge dropped to 25.97 on May 28 from 60.56 on April 30.
In June 2008, a month after the index reached its peak, the Paris-based OECD said the U.S. would grow at a 1.1 percent rate the following year. Commodities continued to drop, and in October 2008, the index fell at a 56 percent annual rate, which was then the lowest level since 1949.
Almost two months later, the National Bureau of Economic Research, the panel that dates American business cycles, said the U.S. was in a recession. The world’s largest economy shrank 2.4 percent, the worst contraction since 1946.
Now, “the collapse in the commodity index is telling us that the peak in global industrial growth is imminent, it’s here right now,” Achuthan said. “Markets are going to have to deal with the reality of a slowdown.”
China’s Purchasing Managers’ Index slid to 53.9 from 55.7 in April, the Federation of Logistics and Purchasing said today. That was less than the median 54.5 estimate in a Bloomberg survey of 18 economists. A monthly gauge of manufacturing in the euro region fell to 55.8 from 57.6, Markit Economics said. The Institute for Supply Management said its U.S. factory index dropped to 59.7 in May from 60.4 in April.
Europe’s debt crisis is only starting to weigh on global growth, said Michael Aronstein, a strategist at Oscar Gruss & Son Inc. who predicted the 2008 commodity plunge and is betting against a rally this year.
The European Union announced an almost $1 trillion loan package last month to halt a slide in the euro and local bonds that threatened to shatter the currency union. Budget cuts across the region may curb demand for Chinese imports as well as commodities including gasoline, aluminum and steel.
Raw materials may drop another 10 percent because the economy is on the “cusp” of deflation, said Philip Gotthelf, the president of Equidex Brokerage Group Inc. in Closter, New Jersey. That would drive the Reuters/Jefferies CRB Index of 19 commodity futures down 22 percent from a Jan. 6 peak and into what investors consider a bear market. The gauge plunged 8.2 percent in May, the most in 18 months.
Gotthelf correctly predicted in October 2008 that oil would fall below $40 a barrel and said he is now shorting most commodities and buying gold.
The CRB index fell 0.9 percent to 252.39 today. Nickel tumbled 4 percent, and crude oil dropped almost 2 percent. …
Euro Outlook
A “wave of fiscal austerity” in Europe will depress the expansion in the region, in the U.S. and in China, according to Arnab Das, the head of global market research at Roubini Global Economics in London. Today, the euro touched $1.2111, the lowest level against the dollar since April 2006, as European unemployment climbed.
Last month, Spain was forced to rescue banks and policy makers including Italian Prime Minister Silvio Berlusconi said they would cut spending to combat a financial “tsunami” in the region.
Investors are getting less bullish, according to the U.S. Commodity Futures Trading Commission. Speculative net-long positions, or bets on rising prices, for 16 commodity futures have dropped 33 percent in the past three weeks, CFTC data show. That’s the lowest level since Feb. 9, after the net-longs plunged 58 percent from a 20-month high on Jan. 12.
“It’s the uncertainty that’s the biggest problem,” said John Kinsey, who helps manage C$1 billion ($995 million) at Caldwell Investment Management Ltd. in Toronto. “Commodities are being attacked with these concerns about the debt situation in Europe and the steps that China has taken to tighten. People are afraid this is going to slow the economy. It’s hard to see a way out of it.”
This is from the Times Newspaper of England:
This is the age of war between the generations
Never mind the credit crunch, it’s all those retiring baby-boomers who threaten us with national bankruptcy
by Anatole Kaletsky
Yesterday was my 58th birthday. If I were a Greek worker I could retire. Although pension payments in Greece normally start around 61, special provisions allow anyone to retire at 58 if they have been in employment for 35 years. That, as it happens, is how long I have been at work. My index-linked pensions from the Greek Government would be worth 75 to 90 per cent of the average salary in the country, guaranteed for the rest of my life by the State.
If you want to know why Greece is going bankrupt and why the euro seems to be on the verge of disintegration, look no farther. The best argument I have ever heard for a break-up of the euro was this observation in a German newspaper: “The Greeks go on to the streets to protest against an increase of the pension age from 61 to 63. Does this mean that Germans should extend the working age from 67 to 69, so Greeks can enjoy their retirement?”
This, however, is not another article about self-indulgent Greeks and self-righteous Germans. The battle over bailouts in Europe is only a sideshow compared with the great social conflict that lies ahead all over the world in the next 20 years. This will not be a struggle between nations or social classes, but between generations — and it is a conflict that, in Britain, begins in earnest this year. The end of the Second World War in May 1945 marked the start of the baby boom, which lasted until the mid-1960s. Now, 65 years later, the corresponding retirement revolution is about to shake up our society, economy and political institutions.
If the word “revolution” sounds like an overstatement, consider the most important issue in British politics today — and then let me draw your attention to the most important book about this issue, written, as it happens, by a senior minister in the new Government. The issue is, of course, the unsustainable size of the public deficit. The book is called The Pinch by David Willetts, the Tory Minister for Universities, and its subtitle conveys his main message with his characteristic clarity and directness: “How the baby-boomers took their children’s future and why they should give it back.”
Mr Willetts shows how the overwhelming size of the baby boom generation, in comparison with the generations just before and after, allowed people born in the two decades after VE-Day not only to dominate culture, fashion and morality, but also to accumulate wealth, monopolise employment and housing and reduce social mobility for the next generation.
But strangely, however, nobody — least of all an active politician like Mr Willetts — seems to make the connection between long-term intergenerational tensions and the present controversies over public spending and taxes.
Why, for example, are governments everywhere running out of money, not just in Britain and Greece, but also in America, Germany, Japan and France? Why are taxes relentlessly rising in all advanced capitalist countries? And why is public spending being cut on schools, universities, science, defence, culture, environment and transport, while spending on health and pensions continues to rise?
The populist answer to these questions is that we are all about to pay for the greed of the bankers. But this is not true. According to IMF calculations, the credit crunch, bank bailouts and recession only account for 14 per cent of the expected increase in Britain’s public debt burden. The remaining 86 per cent of the long-term fiscal pressure is caused by the growth of public spending on health, pensions and long-term care. The credit crunch and recession did not create the present pressures on public borrowing and spending. They merely brought forward an age-related fiscal crisis that would have become inevitable, as by 2020 the majority of the baby-boomers will be retired.
The rational solution to this fiscal crisis would be for governments to reduce their spending on pensions, health and longterm care. Yet these are precisely the “entitlements” protected and ring-fenced by politicians, not just in Britain but also in America and many European countries, even as other government programmes are ruthlessly cut.
The politics of the next decade will be dominated by a battle over public spending and taxes between the generations. Young people will realise that different categories of public spending are in direct conflict — if they want more spending on schools, universities and environmental improvements they must vote for cuts in health and pensions.
Schools and universities are more important for a society’s future than pensions. Yet every democracy around the world has made the opposite judgment. While many politicians claim to be obsessed with education — recall Tony Blair’s three priorities were “education, education and education” — in reality they support health and pensions to the point of national bankruptcy, while squeezing universities. The same applies to the many fiscal benefits heaped on pensioners over the years. Is it, for example, better for society to offer free bus travel to wealthy 80-year olds rather than students or impoverished youngsters looking for their first job?
Why are such conflicts of interest between old and young never debated? Partly because of the myth that pensioners are “entitled” to their many benefits because they have “paid their dues” through national insurance and taxes. This is simply untrue. The true value of the average baby-boomer’s benefits is 118 per cent of the taxes they paid, according to Mr Willetts — and higher according to other calculations.
Second, and more importantly, the baby boomers are so numerous that no politician dares to campaign against their interests. Moreover, older people are more likely to vote. As a result democracies will increasingly be held hostage to the special interests of “grey panthers”, whose power will steadily grow as more baby-boomers retire.
Will politics therefore degenerate into a conflict between the dwindling number of voters with children, who care about education and the future, and the massive power of pensioners with shorter time horizons? Here is a modest proposal to avert this awful outcome. Since children under 18 are not allowed to vote, perhaps pensioners could be deprived of the right to vote after 75 or 80. An equally effective alternative would be to give mothers an extra vote for every child under voting age. Since no such reforms are ever likely, I look forward to the Greek Government being forced to sell the Parthenon — and to Oxford and Cambridge being turned into luxury old people’s homes.
CEO of firm that made $100 million selling ‘scareware’.
IDG News Service: The CEO of a company accused of making more than $100 million selling harmful “scareware” antivirus products was already a fugitive from U.S. authorities, following his arrest in 2008 on criminal counterfeiting charges. Shaileshkumar “Sam” Jain is one of three men who were charged by the U.S. Department of Justice on Wednesday for allegedly operating a massive scareware distribution ring.
He’s now thought to reside in Ukraine, but arrived there only after giving authorities the slip after being arrested by federal agents in 2008 on charges that his company sold counterfeit versions of Symantec antivirus products. Jain has been considered a fugitive by U.S. authorities since early 2009, when he skipped out on a $250,000 bond and failed to show up for a Jan. 12 California court appearance.
Jain ran a Ukrainian company called Innovative Marketing, which prosecutors say sold an astounding 1 million copies of fake antivirus products such as WinFixer, Antivirus 2008 and VirusRemover 2008.
According to court filings, Innovative Marketing was one of several companies that Jain operated, first selling counterfeit Symantec products and later moving into the scareware business with products such as WinFixer.
Symantec had already gone after Jain in the courts, winning a $3.1 million judgment against him in 2005. …
The scareware products that the three men are accused of selling are perhaps the most annoying problems on the Internet, and a constant source of complaints to security companies and federal regulators. They not only fail to protect computers, they often also bog down systems with spyware and malware.
The company would set up fake advertising agencies with names such as BurnAds and NetMediaGroup, and then buy online advertising, pretending that it was for legitimate buyers, prosecutors say. These ads would be programmed to deliver scary-looking pop-up windows straight to users’ desktops. The windows would typically look like Windows error messages or security alerts. To dismiss them, the victim would have to pull out a credit card and pay between $30 and $70 to buy Innovative Marketing’s dubious products, prosecutors say.
Before the scareware came the fake Symantec software. Prosecutors allege that in 2003 and 2004, Jain operated a handful of Web sites — Discountbob.com, shopenter.com, winantivirus.com and others — that all sold fake Symantec products. Jain allegedly drummed up new business by spamming victims or using pop-up ads to flog the fake software, which was then mailed out by someone identified in court documents as “J.R.” of Amelia, Ohio — presumably James Reno. …
Osama bin Laden admits to major inadequacy.
In a new video that is light on his usual threats but heavy on admiration,
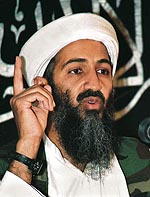
Osama bin Laden admits that he is “professionally envious” of oil giant BP’s massive oil spill, saying that it puts his efforts to create destruction and chaos to shame.
“There are times in an evildoer’s life when one has to stand back and admire a job well done,” Mr. bin Laden says in the video. “BP, you blow me away.”
The Al-Qaeda mastermind adds that his first thought upon seeing BP’s spill was, “Man, I’ve got to step up my game.”
Mr. bin Laden claims in the video that he rarely feels envious towards other evildoers, but says he likes “to use that energy to push myself to be the best terrorist I can be.”
As for the envy he felt after seeing BP’s handiwork, the madman says, “I haven’t felt this way since the whole Toyota thing.”
Harry Newton, who wonders about a serious double dip recession. He also wonders about all the talk about “no inflation.” My best source of on-the-ground economic information, my local pizza owner, says everything he buys from plates to garbage cans to pizza ingredients has recently gone through the roof. The cost of much of his supplies has doubled in the past year. He’s horrified. He can’t raise his prices. His customers won’t take it. Meantime, his sales are down — 20% from two years ago.

do you people still believe in existence of some bin Laden????