Recession talk has ebbed. The market is at peak. Earnings are OK. The banks are in good shape. Everyone has a job.
It’s the weekend. I just lost at tennis. I’m depressed. I’m mulling about the next recession.
Recessions are typically caused when assets owned by many people (and institutions) suddenly become worthless.
They become worthless for many reasons: Stocks turn down because people suddenly feel differently. Housing prices stop rising. Mortgages start defaulting. Last year’s great business project now looks awful.
Things change in peoples’ brains.
The last recession — 2008 — came because mortgages started defaulting. The causes were obvious. Many of the mortgages were pure garbage. They were created by mortgage brokers paid huge fees to create mortgages which could be bundled up, painted with lipstick (made to look solid and enticing) and then sold (at a profit) to dumb institutions (many overseas), who had more money than sense — and had never met a Florida mortgage broker.
The buyers of bundled mortgages ignored that the companies rating these mortgages (called rating agencies) were paid fees by the bundlers to attach a handsome, solid rating to the mortgage bundles. (They still rate muni bonds.)
The mortgages weren’t solid. They were created to earn fees and to move on (sell), not to hold. The mortgages were known as liar loans (the borrower lied about his income) and ninja loans (no income no job). They were often taken out on homes the buyers (also called flippers) were going to flip (sell) quickly at a higher price. God willing.
When house prices suddenly stopped rising, the mortgages started defaulting, the bundles of “high-grade” housing mortgages became worthless and started defaulting. Bingo we had The Great Recession 2008.
Now? Typically we have recessions every ten years or so. We’ve defied that timing. The stockmarket is at peak and America is still binging on borrowing — though standards today seem a tiny bit tighter than 15 years ago.
Now the fear is that the ultra-low interest rates we enjoyed for the past ten years have caused corporations to do what housing flipper/speculators did in 2005, 2005, 2006, etc, — binge on borrowing. Now the fear is that many over-extended companies may not be able to pay the interest on their borrowings, and may not be able to repay their loans. They may default and bingo we have a recession.
Ed Yardeni who’s just written a book called Predicting The Markets and is finishing up his new book Fed Watching for Fun and Profit: A Primer for Investors. writes in his blog:
Central banks fuel deflation by feeding zombies. My interpretation of the data is that excessively easing credit conditions fueled the mortgage borrowing binge and housing boom that ended with the Great Financial Crisis. The strong debt-financed demand for homes stimulated economic activity and caused home prices to soar.
Since the Great Financial Crisis, the borrowing binge in NFC (non financial corporate) debt hasn’t contributed much to economic growth, and consumer price inflation has remained subdued. Apparently, a significant percentage of NFC debt is attributable to zombie companies using most of the proceeds from their borrowing to stay in business. The Fed’s May 2019 Financial Stability Report nailed it, as follows:
“The risks associated with leveraged loans have also intensified, as a greater proportion are to borrowers with lower credit ratings and already high levels of debt. In addition, loan agreements contain fewer financial maintenance covenants, which effectively reduce the incentive to monitor obligors and the ability to influence their behavior. The Moody’s Loan Covenant Quality Indicator suggests that the overall strictness of loan covenants is near its weakest level since the index began in 2012, and the fraction of so-called cov-lite leveraged loans (leveraged loans with no financial maintenance covenants) has risen substantially since the crisis.”
During his 10/30 press conference, Fed Chair Jerome Powell was asked about financial stability. He responded: “Obviously, plenty of households are not in great shape financially, but in the aggregate, the household sector’s in a very good place. That leaves businesses which is where the issue has been. Leverage among corporations and other forms of business, private businesses, is historically high. We’ve been monitoring it carefully and taking appropriate steps.”
He didn’t specify those steps. However, the Fed’s three interest-rate cuts are likely to feed the zombies’ appetite for more debt. In other words, the easy money provided by the Fed and the other central banks may be contributing to deflationary pressures attributable to supply-side borrowers. This would certainly explain why easy money has failed to boost inflation as expected by the proponents of demand-side models.
Is a zombie apocalypse inevitable? If you want to read a very frightening script of how this horror movie plays out, see the October 2019 Global Financial Stability Report prepared by the International Monetary Fund. Here is the punchline: “In a material economic slowdown scenario, half as severe as the global financial crisis, corporate debt-at-risk (debt owed by firms that cannot cover their interest expenses with their earnings) could rise to $19 trillion-or nearly 40 percent of total corporate debt in major economies, and above post-crisis levels.”
There’s certainly lots to digest and think about in this unsettling report as the S&P 500 climbs to another record high. Apparently, investors expect that before doomsday arrives, even the Fed will lower interest rates close to zero again, allowing all the zombie borrowers to refinance their debts, thus postponing the zombie apocalypse.
The basic problem — this is Harry speaking — is
There’s too much money around. There aren’t enough opportunities to invest it. This has several consequences:
+ People and institutions get desperate with their money and invest in junk.
+ Governments binge on cheap borrowing. The U.S. government is a prime binger, irresponsibly running up its deficit and its debt.
+ Pensions are in big trouble. How big? Read the Financial Times
Their house is on fire’: the pension crisis sweeping the world
Click here.
Recently, I have personally watched as companies recently have gotten themselves into trouble by expanding too fast. For egregious expansion, check out the IPO market. But I can also name you a bunch of private companies.
To mix my metaphors:
+ I don’t know when the chickens will come to roost.
+ I do know there are canaries in the mine looking wan.
I’m not reducing my exposure to stocks. But I am keeping five years of living expenses in cash.
Of course, that means that I am making assumptions about how much my family will spend. It’s called a budget.
The last time the family had a “budget” was Claire’s wedding. How did that work out? Not good. It went more than twice over budget.
When I questioned that, I heard:
+ It was a nice wedding.
+ It’s your daughter.
+ It is what it is.
And everything still is.
Useful stuff
+ For cash, the VMFXX money market (from Vanguard) is much better than Fidelity’s SPAXX which I’ve been stupidly using. Holdings in the two funds are basically the same. But VMFXX’s expense ratio is much much lower. And therefore the return to me — cash in my pocket — is much higher.
+ Lands End is offering 50% off on just about everything. To me, their “best’ is their stuff in “tall.” They also have great casual boots.
+ Boeing’s FAA and overseas regulator approvals for the 737 MAX may be delayed even further. The headline on the story is FAA loath to rush test to clear max. Click here. None of this bad press stops Boeing’s stock from going up. To me, Boeing remains the classic cockroach stock, with a litany of bad news to pop out over time. A five minutes ago I shorted Boeing (again). I’m up enough to buy a cheap lunch. This time I’m day-trading Boeing — not holding it overnight. When I make a few bucks, I’m out. My friend calls it a haircut.
+ How good are Apple’s AirPod Pros? True story: I’m listening to Mozart in the bathroom. The AirPod Pros are so good at noise cancelling, I couldn’t hear the toilet flush. I flushed it several times before I figured out I was an idiot, and wasting water.
This is Claire Elizabeth Newton
She was six, maybe seven. She was cute and wore black Mary Janes, which I loved.
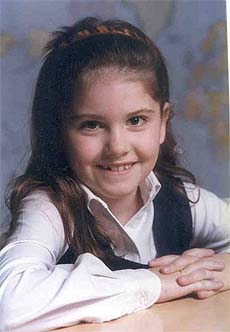
Today she told me the biggest lesson she ever learned from me, her father, was:
You can’t believe what you read.
When I asked why, Claire told me I replied:
I write the stuff.
Depressing.
Gives fake news a whole new meaning.
This is Zoe, Claire’s daughter and my granddaughter
They took her recently to the Bowdoin College cafeteria in Maine and tried to feed her Jello — for the first time.
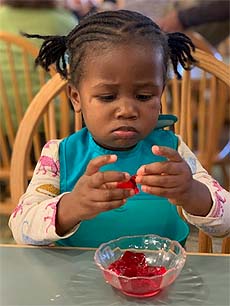
Poor kid. They didn’t give her a spoon. Some sort of Mummy torture. Zoe examined the Jello, played with it and finally rejected it. This made her mother very happy. To Claire, anything with sugar in it is the work of the devil.
Our stocks are up today, except Boeing which is down. Yipee.

Harry, your longtime reader, big fan and occasional commenter on this website, Toby Bugfoot, has died. He was 49 and suffered a massive stroke about nine days ago. Toby was born in 1969 and passed away on Sunday. I know you thought that was a made up name at times but I assure you that Toby was real and his obit can be found in the New York Times. He turned me on to your website in 2017. We’re never guaranteed tomorrow, so make the best of today.