Gold is the best hedge against industrials that go down with the mess in the world.
The BIG mess is Europe. The little mess is the U.S.
Europe is muddling along, not solving anything long-term. The U.S. is improving, albeit slowly and, sadly, with zero help from Washington.
The Australian CD. Wow, for the first time, I think I understand. Here am I waxing enthusiastically about my Australian CDs. And suddenly I’m faced with real people who’ve written to me saying they’re interested. I’m sort of freaked. What if something went wrong? I’d feel really awful. I wonder if brokers and investment advisers feel this way? I bet the good ones do. Sadly, there aren’t many of them.
Suffice, I do like my Australian bank CDs. Last night I wrote a long piece to send to readers who are interested in the Australian CDs. I’ll email it out as soon as I post this column — about 9:15 AM.
If you want a copy, email me.
Meantime, there are two risks:
1. You’re buying CDs in Australian dollars. The Australian dollar is presently high – around $1.05. In other words, Australian dollars are presently worth more than American dollars. That could change. The Australia dollar could fall. The American dollar could rise. That’s called exchange risk. I’ve lived with this risk for years. So far, the Australian dollar keeps rising. Australia is actually in much better shape than America, with much faster growth and much lower sovereign debt to GDP ratio – I had a chart on the blog a few days ago. But things change.
2. Your CD is not guaranteed by the FDIC or the Australian government. It’s guaranteed by Westpac, which has a double AA rating by Fitch and Standard & Poors and a Aa2 rating by Moody’s. I don’t see Westpac, Australia’s largest or second bank (depending on how you measure it), failing. But stranger things have happened.
There are some issues:
1. You have two choices. Send Westpac your money in Australian dollars or send it in American dollars. My recommendation is to shop around and get the best rate and send the money in Australian dollars. That way you know what you’re getting. Banks, being banks, offer differing rates. The rate you see on Bloomberg or Yahoo Finance isn’t necessarily what you get. And you can –- I’ve discovered –- bargain exchange rates, like you can everything else. (In fact, American banks routinely rip you off on your foreign exchange dealings. Check out the 3% Visa charges when you visit France. Fortuntely, Capitol One and Amex don’t charge you the 3%) Check. Check. Check.
2. The Australian government takes 10% of your annual interest earnings. You get the remaining 90%. I choose to have my interest reinvested. You should be able to deduct that 10% from your U.S. federal taxes since Australia and the U.S. have a double taxation treaty.
3. Sydney, Australia is 14 hours ahead of EST. You call Australia when it’s our nighttime.
4. They speak Australian, which is a form of English somewhat understandable to Americans.
5. Sadly, I don’t make anything on any monies you invest in Australian CDs. I am not Westpac’s agent. I simply wrote about my excitement for Australian CDs, like I wrote about my excitement for gold, which has worked out fine (excluding yesterday).
Dipping into your bank account. Here’s my bank’s latest stunt. My american bank dipped into my bank account to take $47.50 for rental of my safety deposit box plus (get this) $15 in late fee because they were late deipping into my bank account. Of course, they did all this without telling me. And not for the first time. Increasingly, they’re helping themselves to all sorts of spurious charges and fees. Alll banks are doing this.
The only solution is to check each bank statement carefully and then demand your money back from your local bank manager or his boss. You’ll get the money back. But the whole process is a pain.
It seriously annoys me when they charge me $13 for each incoming wire. Strikes me they should be happy for the new money… What do I know about banking greed? Except it has no bounds.
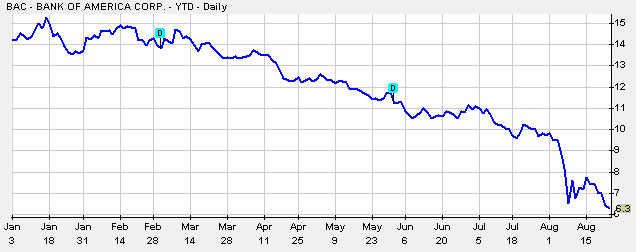
Meantime, my favorite incompetent bank, BAC, continues to fall. Don’t short it here. however:
HDR photography. The iPhone (and some digital cameras) have HDR. I always use HDR when I take photos with my iPhone4. HDR makes my photos better. Here’s Apple’s explanation:
Just point iPhone 4 at your subject and shoot. iPhone 4 automatically captures three photos of the scene — each with different exposure levels. Then iPhone 4 layers the shots together to create a single photo that combines the best elements of each shot and more accurately represents the wide range of light in the scene. Both the regular shot and the HDR photo appear in the Camera Roll. Here’s Apple’s example:
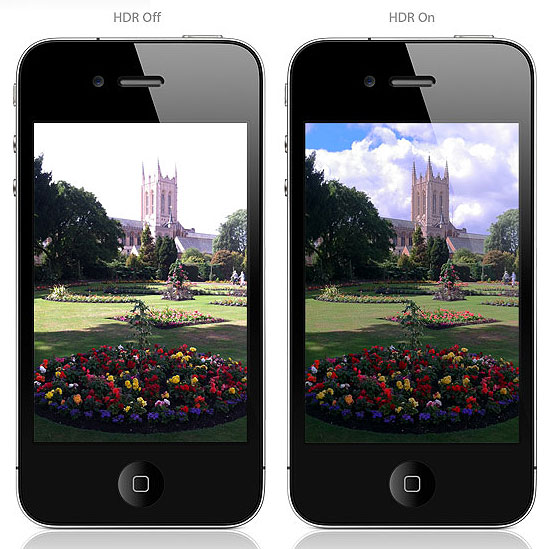
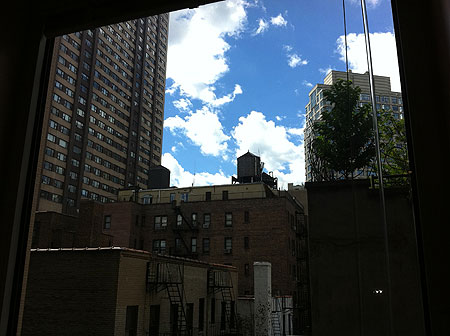
I think Apple’s photos are a little fakey. Here are my results. This is the gorgeous view from my home office — without HDR.
This is the with HDR:
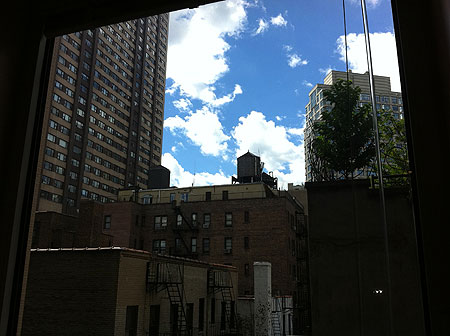
Better. Sometimes, it works even better. I always turn on HDR.
Wikipedia explains HDR:
In image processing, computer graphics, and photography, high dynamic range imaging (HDRI or just HDR) is a set of techniques that allow a greater dynamic range of luminance between the lightest and darkest areas of an image than current standard digital imaging techniques or photographic methods. This wide dynamic range allows HDR images to more accurately represent the range of intensity levels found in real scenes, ranging from direct sunlight to faint starlight.
The two main sources of HDR imagery are computer renderings and merging of multiple photographs, the latter of which in turn are individually referred to as low-dynamic-range (LDR) or standard-dynamic-range (SDR) photographs.
The world’s best new toy. It’s called AirSwimmer. Click here. Buy it on Amazon.
Is the SEC Covering Up Wall Street Crimes? The simple answer is YES. Matt Taibbi reports:
A whistle-blower claims that over the past two decades, the agency has destroyed records of thousands of investigations, whitewashing the files of some of the nation’s worst financial criminals.
For the full story, click here.
World’s best airline — Cathay Pacific. We flew New York to Hong Kong and then to Perth Australia. I carried a tiny Swiss Army knife, the smallest they make. They ignored it in New York but confiscated it in Hong Kong. They gave me a receipt. On return to New York, I sent the receipt to Cathay asking for my knife back. I expected nothing. But… several days late I receive this enormous 14″ box:
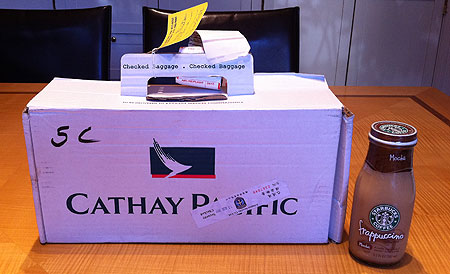
Which contains, guess what,
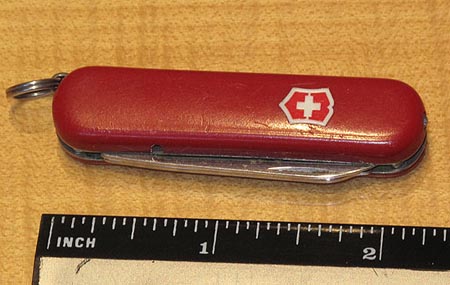
the world’s smallest swiss army knife. It’s customer service stories like these that make you tear up. Thank you Cathay Pacific. I will always fly you. I do love your flat beds in business class.
Favorite recent New Yorker cartoons.

Harry Newton who wonders why there are so many young fat people working in health care. Dont they — of all people — realize the consequences? Diabetes, heart disease and now there is evidence that obesity can actually cause cancer.
A reader wrote to me this morning, “You have Wall St. pegged correctly – their sole goal is to separate you from your money. If you understand that, then you can invest successfully.” Amen.

Great video of Steve Jobs speech – 'How to live before you die'
http://www.ted.com/talks/steve…
Thanks for the link…15 minutes to view is time well spent!
Westpac is a solid, reputable bank – I doubt they are going anywhere south soon. Their stock value might fluctuate in the next few years but the bank wouldn't disappear without a whole lot of warning signals.
The Reserve Bank of Australia (who sets interest rates) is in a 'war of charts' (IMO) with the banks – raw economic data suggests that inflation is a little high and the interest rate could be pegged a little higher to deal with it. The banks oppose this view and are putting pressure on the RBA by unleashing endless stories/reports through the media that suggest interest rates should be reduced or at least left where they currently are.
Behind it is this: from 2000 to 2010 Australia has seen 10 years of explosive real estate prices fuelled by speculative buying (which the banks have funded with variable rate loans) which has left Australia with an over-priced real estate problem. At the moment (since 1st qtr 2011) real estate prices have stalled and if they continue to do that for a few more years (10 at least), things should settle down again. But a bump of 1% to the RBA interest rate will make a lot of people realise they have a loan for $900,000 on a property that the market will pay $650,000 for – and that causes all sorts of problems for the banks.
In short – Westpac isn't going anywhere with your deposits, and interest rates should actually increase in the next twelve months (but not by much).
As for the exchange rate – i can't help you with that. The AU$ has broken all records with the US$ recently, and I moved my money into index based ETF's available on the NYSE when the market fell a few weeks back. I'm kinda hoping it drops 10 to 15c in the next 12 months.
If you're unhappy with your bank, try credit unions. Alliant Credit Union is easy to deal with, with very competitive rates. I can deposit checks into my account by scanner, using their software, and they have a robust network of ATMs. They're at – http://www.alliantcreditunion….
Thanks for all your work an suggestions. I appreciate your CAUTION regarding Australian CDs; I remember your temporary disillusion after your initial investment experienced an exchange rate (paper) loss.
Can anyone please tell me if Peter Lik uses HDR. Peter is like a used cars salesman and the same holds true for the people that work for him but he has very cool photos which are obviously overpriced but pretty stunning…The salesman say he doesn't manipulate his photos but he must use HDR or a neutral density filter and illustrator???
Speaking of healthcare workers. I love it when you go to your doctors office and some of the employees are standing outside smoking cigarettes!!!!!! Makes me feel really confident in their ability to help me.
When I used an HMO in New York, I used to have to walk through a choking cloud of cig smoke to get into the building to see my doctor.