You pay $1,000 for an investment that drops $100 to the bottom line. That means you’re earning 10%. Now borrow $750 at 6%. That means you’ll pay $45 in interest. Your profit will drop to $55. But now you only have $250 invested. So your rate of return rises from 10% to 22%.
Ah, the joys of borrowing, also called leveraging or a free lunch.
Free lunches have costs:
First, your investment has to throw off at least $45 to pay the interest on the loan. Otherwise, you’ll go into default and the bank will snatch your investment. In short, be nice to your tenants and pray they’re not another Circuit City.
Second, your loan will come due at some point. You’ll need to pay off the bank, or negotiate an extension to your loan.
I am investor in many buildings, also called syndicated real estate.
Most (not all) of my buildings (also called real estate syndications) are earning enough to pay the bank its interest.
The big problem we face is when our loan comes due, which soon.
These days banks have new ideas about lending on real estate. For one, they believe the value of our building has declined. Second, they won’t lend the 75% of its value they used to. They’ll lend maybe 65%. And that will be on a lower building valuation.
So we may have a loan coming due of $5 million. But the bank will now only lend us $3 million (even though we paid their interest on time, never a day late). We now have three alernatives:
1. Beg the bank to extend the loan. Perhaps pay a higher interest rate as part of the extension deal.
2. Get the investors in the syndication to pony up $2 million more in capital. Difficult, if not impossible, in most cases.
3. Let the bank foreclose on the property. In other words, lose it. get on with our lives. Play tennis.
Until judgement day — the day the loan comes due — there are various strategies the management of a syndication can do:
1. Make the assumption you will lose the building to the bank. In the meantime, cease maintenance and improvements. Suck the building dry of every nickel. Pay out everything possible to investors.
2. Cease paying anything to investors. Accumulate a “war chest” that could be used to motivate the bank when Judgement Day arrives.
How bad is it? It’s bad. Virtually every piece of commercial real estate in the U.S. is now worth less than the loan on it. In the trade they call that “upside down.” There are no easy answers.
Some banks are foreclosing, and taking on managing their new properties.
Some banks are working deals with owners, believing the owners are better managers than the bank.
Some banks are just prolonging the agony, often extending the loan for a few more months and then for a few more.
I figure virtually all my commercial real estate syndications are upside down. It’s not pleasant. I’m slowly writing down each of these investments to $1 — if only to continue reminding myself of how stupid I was. I wonder if the banks are also writing down their loans to their new, much lower value. Most aren’t. They have faith-based accounting. For me, I’d prefer reality accounting, no matter how painful.
All my residential real estate — what I live in and rent out — don’t have mortgages. That’s comforting.
Another new folding electric bike. this one from VW.
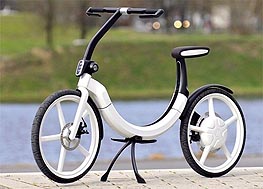
It folds into the spare tire well of your VW and is recharged while in the well.
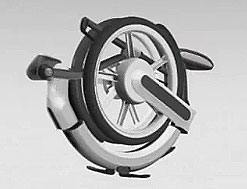
It has a range of 12.5 miles and is impressively light. You easily lift it.
I ride around New York on the Dahon Mu SL:
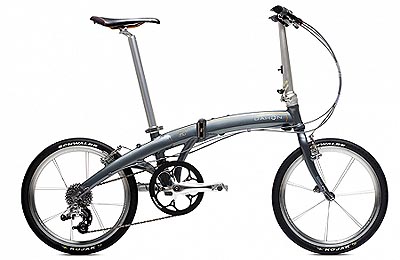
It weighs around 20lbs. For a bike that’s light. It folds quickly and neatly for taking into buildings and restaurants and storing in coat closets:
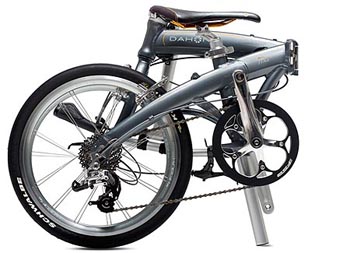
It doesn’t have a motor. You have to pedal it. But it’s easy, good exercise and a joy to ride. It has nine gears. It takes about 30 seconds to fold or unfold. Highly recommended. Click here.
Maybe this is true.
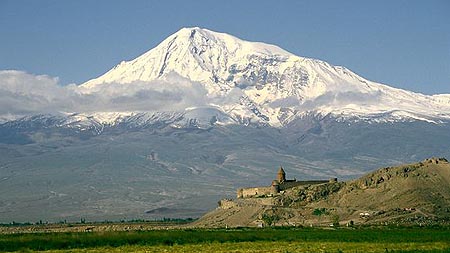
Explorers say they found Noah’s Ark near the top of Mount Ararat in Turkey (here seen from Armenia). Photo by Martin Gray, National Geographic.
The pleasures of napping. There’s huge research on sleeping. We sleep too much. We sleep too little. We sleep at the wrong times. Fact is you have to work out what works best for you.
I prefer two short naps in the day. One at lunchtime before I play tennis. And one in the evening after dinner. I’ll then work late at night when it’s quiet. I often awake at 5 AM and work a little more.
My friends tell me (a) they’re sleep deprived, and (b) they can’t nap. I explain to them that napping is a learned skill. Pretend you’re an Egyptian mummy. Place your crossed hands on your chest. Close your eyes and focus on trying to get your under hand to not feel your upper hand and then to float. Bingo, you’re gone. Twenty minutes can make you feel like a new person.
When you’re tired, you make dumb decisions. You get irritated. And worse, your rundown body is susceptible to all sorts of nasties.
You can nap. Trust me.
Harry Newton, who napped yesterday before tennis and played spectacularly (though he still lost).

Harry…I nap every day and find my best “nap aid” to be my Lazy-Boy recliner and eye shades.
On bank lending for commercial real estate. Much smaller issue, however, I have carried $575,000. on Sun City condos, interest only for the past 6 years at M&I Bank. I own the condos outright. I had the money lent out at 12% and traveled around the world on the interest I was making. Day of reckoning came last month. Bank now wants their money back. They wrote a new note, only increased the interest rate by 3/4 of a percent and only wrote the note for ONE year. They did say that if I make the increased principal payments, that I had suggested to accelerate the payback, they would then rewrite the note at the end of the one year. They want to make sure I make good on my promise. I have no reason not to. I am beginning to slowdown my travels anyway. More Lazy-Boy time!
Lucky
Banks are scared and hence irrational. What bank would, in its right mind, make interest-only loans for six years? One that expected real estate prices to rise endlessly. Obviously those days are over. I'm guessing it will be years before banks act the way they in my father's day — community-, customer-focused.