Apple’s bonds are not for you and me. They’re for institutions desperate to earn a few more shekels than they can on US treasuries. Apple’s miserable rates:
3 year bonds = 0.51%
5 year bonds = 1.076%
10 year bonds = 2.41%
30 year Bonds = 3.883%
5 year floating rate bonds = 3month Libor + 0.20% = 0.474%
Apple is borrowing $17 billion, though it has $145 billion in cash, because much of that $145 billion is overseas and it’s cheaper to borrow than to pay the US tax on bringing the monies home. That shows you how screwed up our tax code is.
Apple’s bonds are so popular (they were five times oversubscribed), they may actually be bid up — driving their effective yields below the miserable offering rates (see above).
Some think Apple’s stock now has greater appeal — what with the higher dividend (yield is just under 3%) and the buyback. Me? I’m dubious. Steve is gone. The product pipeline is empty. Management is disarray. But, the stock is most unlikely to fall from here. Consider selling some put options.
Apple stories:
+ The Wall Street Journal. Click here.
+ The new York Times. Click here.
Will interest rates ever rise? 10-year treasuries are presently yielding 1.67%. A guru predicts that they’ll drop to 1% by the end of this year. And they won’t rise until 2018 at the very earliest. The man has been right on with his interest rate predictions over the last several years.
So what do you do with your money?
The stockmarket? That’s it. And that’s why it’s going up, despite desultory economic news — though buoyant earnings from selected companies (see list on right for latest sock recommendations).
Search for the Perfect Bank — part 3. Items:
1. My present bank took eight days to authorize a refund of $315 in $13 fees they’d charged on wires incoming into my account. My local bank manager had to escalate my request since his authority was capped at $300. Still no permanent fix — removing the fee altogether. And no photo deposits, i.e. taking a picture of a check and emailing to the bank, instead of schlepping or mailing it.
2. Another bank offered a seminar featuring Austan Goolsbee, the ex-chairman of Obama’s President’s Council of Economic Advisers, which I may actually attend. I get a free breakfast if I get there in time today.
3. My friend, the eminent banker, explained that “Banking sucks. Nobody wants your money since they can’t make any money on it at today’s horribly low interest rates. You’re the worst banking customer, since you don’t borrow. And you’re very demanding.”
+ Chase has a private bank around the corner with a zillion ATM machines. Maybe there is charm in a big bricks and mortar bank within walking distance — about 500 yards?
In Venture Capital Deals, Not Every Founder Will Be a Zuckerberg. How venture firms use preferred shares to ensure their returns (and often screw the founders) This New York Times piece is fascinating. Click here.
Everything Is Rigged: The Biggest Price-Fixing Scandal Ever.
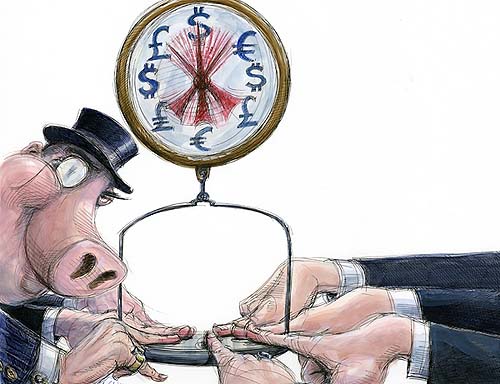
Matt Taibbi’s latest piece in Rolling Stone begins:
Conspiracy theorists of the world, believers in the hidden hands of the Rothschilds and the Masons and the Illuminati, we skeptics owe you an apology. You were right. The players may be a little different, but your basic premise is correct: The world is a rigged game. We found this out in recent months, when a series of related corruption stories spilled out of the financial sector, suggesting the world’s largest banks may be fixing the prices of, well, just about everything.
You may have heard of the Libor scandal, in which at least three – and perhaps as many as 16 – of the name-brand too-big-to-fail banks have been manipulating global interest rates, in the process messing around with the prices of upward of $500 trillion (that’s trillion, with a “t”) worth of financial instruments. When that sprawling con burst into public view last year, it was easily the biggest financial scandal in history – MIT professor Andrew Lo even said it “dwarfs by orders of magnitude any financial scam in the history of markets.”
That was bad enough, but now Libor may have a twin brother. Word has leaked out that the London-based firm ICAP, the world’s largest broker of interest-rate swaps, is being investigated by American authorities for behavior that sounds eerily reminiscent of the Libor mess. Regulators are looking into whether or not a small group of brokers at ICAP may have worked with up to 15 of the world’s largest banks to manipulate ISDAfix, a benchmark number used around the world to calculate the prices of interest-rate swaps.
Interest-rate swaps are a tool used by big cities, major corporations and sovereign governments to manage their debt, and the scale of their use is almost unimaginably massive. It’s about a $379 trillion market, meaning that any manipulation would affect a pile of assets about 100 times the size of the United States federal budget.
Read Taibbi’s entire piece here.
See also “Banks resist strong controls of foreign derivative bets.” Click here.
TULIPMANIA: How An Entire Country Once Went Crazy For Flower Bulbs.
The trade proved irresistible. “He who considers the profits that some make every year from their tulips will believe that there is no better Alchemy than this agriculture,” a contemporary poet wrote. A Businesss Insider story. Click here. Plus 16 Big Bubbles That Are Getting Ready To Burst. Fram farmland to bitcoins, to guns and ammo, to contemporary art and commodities. Don’t get too excited about the predictions. The photos are neat, however. Sample:
For Business Insider’s 16 “bubbles,” Click here.
Three favorite New Yorker cartoons.
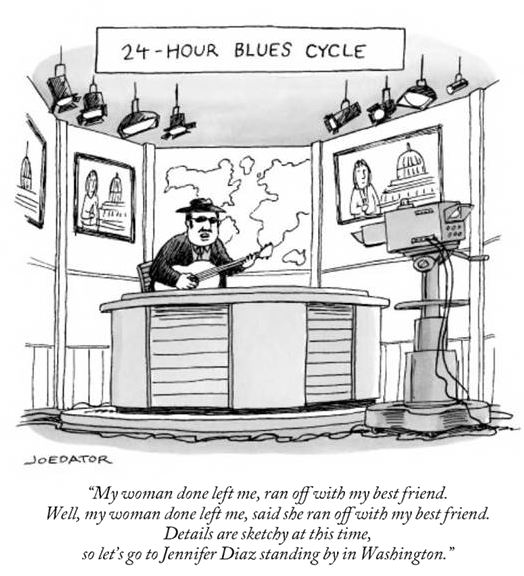
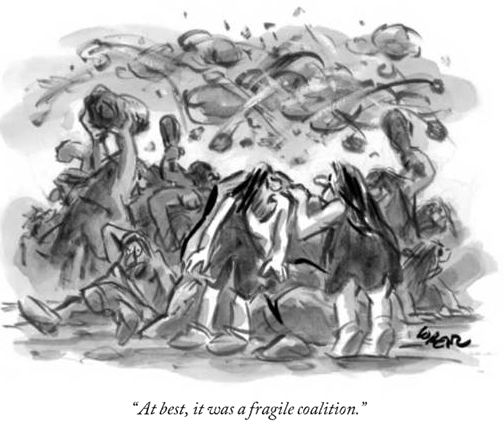

Harry Newton whose son Michael is in Saigon — 100 degree heat and 100% humidity. What pleasure. He reports everyone is dancing Gangnam Style. For PSY’s latest video, click here. I still prefer his original one, which has now reached an incredible 1.6 billion views on YouTube. Click here. Do it.
I took Cramer’s advice and bought a little ETN, PPG and JNJ. I am pleased to report that my four private equity picks — APO, BX, CG and KKR — are all dong well. They’re still worth investing in.

Harry, I think it’s time to clone Steve and save Apple, if it’s not too late. As they say though, when the founder of a great company leaves, it’s time to move on.
Thanks Harry. Your best piece in a long time. Your attached articles saved me a lot of time. You are so correct re the Avoidance of US taxes being the reason for the Apple debt issue.
How can it ever be changed if Wall Street gets paid for the debt issue?